Related Blogs

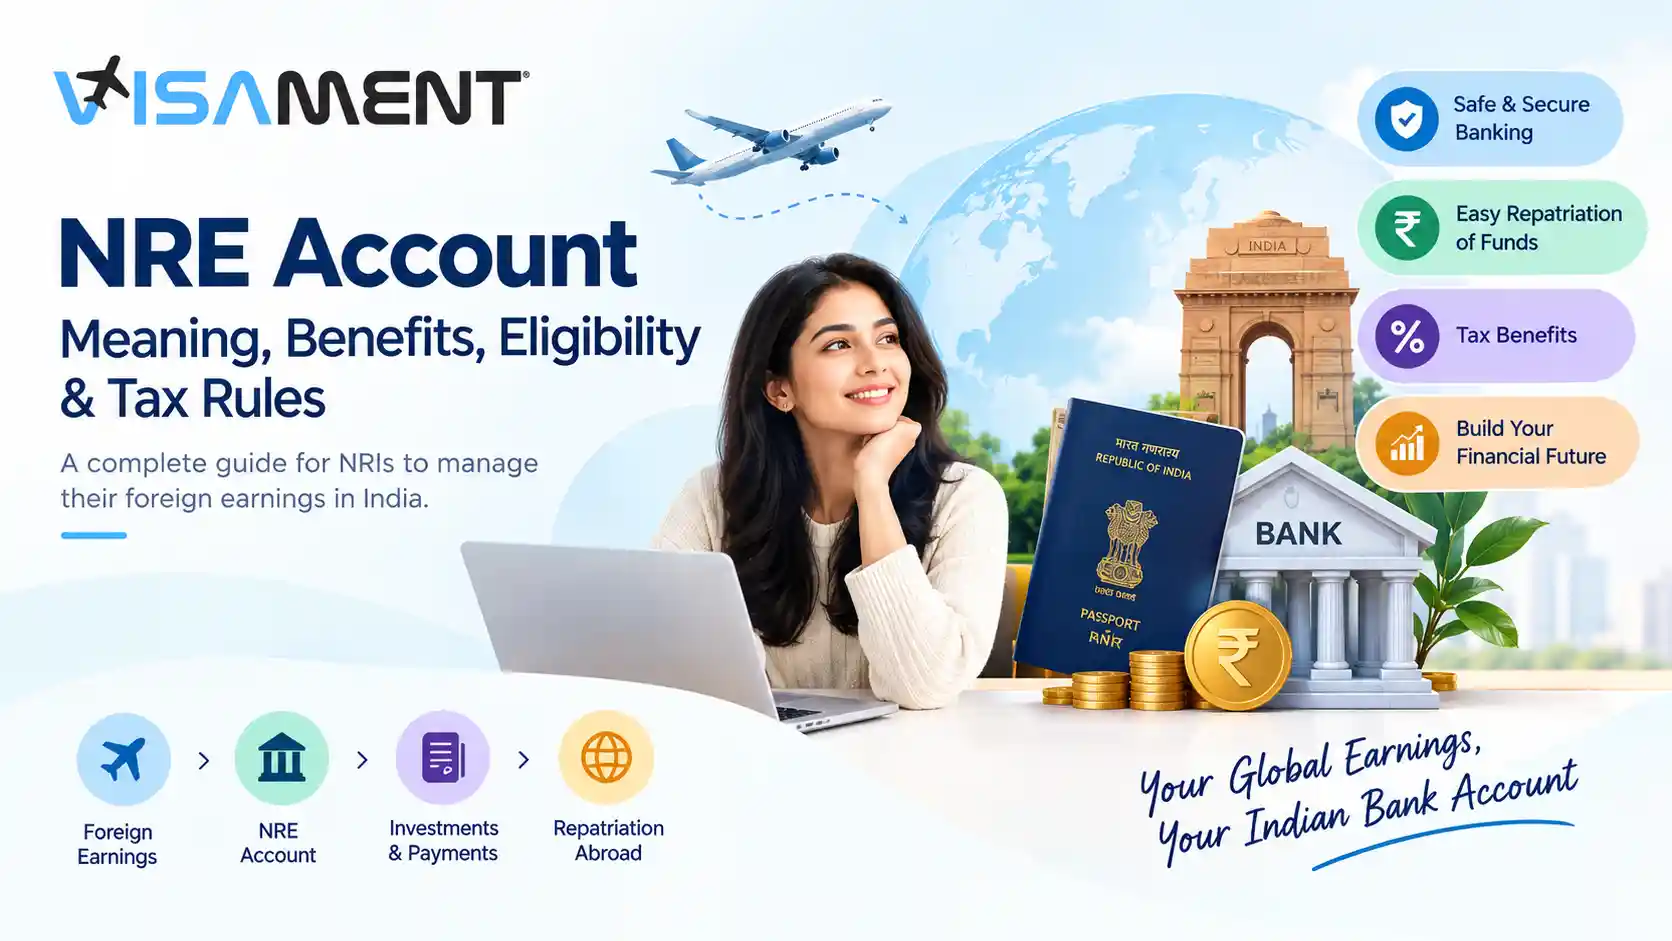
Managing your finances across two countries can be challenging, especially if you're an NRI earning income abroad while maintaining financial commitments in India. Choosing the right bank account is essential to transfer, save, and use your money efficiently.
An NRE (Non-Resident External) Account is designed specifically for Non-Resident Indians (NRIs) to park their foreign earnings in India. This guide explains what an NRE account is, who can open one, its key features, and why it is one of the most popular banking options for NRIs.
An NRE (Non-Resident External) Account is a bank account that allows Non-Resident Indians (NRIs) to deposit money earned outside India while maintaining funds in Indian Rupees (INR).
When you transfer foreign earnings—such as your salary, business income, or savings—from abroad, the bank converts the amount into Indian Rupees at the prevailing exchange rate before crediting it to your account.
An NRE account helps NRIs:
Since the account is specifically intended for foreign earnings, income generated within India generally should not be deposited into an NRE account. For managing Indian income such as rent, dividends, or pension, an NRO Account is typically the appropriate option.
Quick Answer: An NRE account is a rupee-denominated bank account that enables NRIs to deposit foreign earnings, earn interest, and repatriate both the principal and interest, subject to RBI and FEMA guidelines.
Only individuals who qualify as Non-Resident Indians (NRIs) under applicable Indian regulations are eligible to open an NRE account.
Generally, the following individuals may open one:
Individuals residing in India are generally not eligible to maintain an NRE account. If an NRI permanently returns to India and becomes a resident under applicable regulations, the account usually needs to be redesignated or converted according to RBI guidelines.
An NRE account can generally be held:
Banks may have specific documentation requirements for joint account holders, so applicants should verify the latest guidelines before applying.
An NRE account offers several features that make it suitable for NRIs managing international finances.
Although deposits originate in foreign currency, the balance is maintained in Indian Rupees (INR). Currency conversion takes place when funds are credited.
The account is intended for income earned outside India, including:
Indian-source income is generally managed through an NRO account instead.
One of the biggest advantages of an NRE account is that both the deposited amount and the earned interest are generally fully repatriable, subject to RBI and FEMA regulations. This means funds can usually be transferred back to the account holder's overseas bank account without major restrictions.
Interest earned on an NRE account is generally exempt from Indian income tax while the account holder qualifies as an NRI under the applicable tax laws. However, tax obligations in the country of residence may still apply.
Banks typically offer NRE accounts in different forms, including:
This flexibility allows NRIs to choose an account based on their financial goals.
Most banks provide convenient digital banking facilities, including:
These features make it easier for NRIs to manage their finances from anywhere in the world.
Many NRIs continue to have financial responsibilities in India even after moving abroad. An NRE account offers a practical solution by allowing them to keep their overseas earnings accessible in India without compromising flexibility.
Common reasons for opening an NRE account include:
Suppose an engineer working in Canada wants to send part of their monthly salary to India to support parents and invest in mutual funds. Instead of making multiple remittances each time, they can transfer funds into an NRE account, where the money is converted into INR and can be used for eligible financial transactions within India.
An NRE account is designed to help NRIs manage their overseas earnings in India while enjoying flexibility in transferring and using their funds. Here are some of its key benefits.
An NRE account allows you to transfer your foreign earnings to India through banking channels. The remitted amount is converted into Indian Rupees (INR), making it convenient to pay household expenses, invest, or maintain savings in India.
One of the biggest advantages of an NRE account is that both the principal amount and the interest earned are generally fully repatriable. This means you can transfer your money back to your overseas account without requiring prior approval from the Reserve Bank of India (RBI), subject to applicable FEMA regulations.
Interest earned on an NRE account is generally exempt from income tax in India while the account holder continues to qualify as a non-resident under FEMA and the applicable provisions of the Income Tax Act. However, the interest may be taxable in your country of residence depending on its tax laws.
Most Indian banks provide online banking facilities for NRE account holders, including:
Internet and mobile banking
International fund transfers
Debit cards
Online bill payments
Fixed deposit creation and management
These services allow NRIs to manage their finances from anywhere in the world.
Funds held in an NRE account can be used for eligible investments in India, including fixed deposits, mutual funds, shares (subject to applicable regulations), and certain real estate transactions.
Generally, yes. Interest earned on an NRE account is exempt from income tax in India as long as the account holder qualifies as a non-resident under FEMA and is permitted to maintain the account.
Keep in mind:
Tax residency rules differ between countries.
Some countries tax worldwide income, including interest earned outside the country.
If you are unsure about your tax obligations, consult a qualified tax professional.
If you become a resident in India again, you generally cannot continue operating the account as an NRE account. Banks typically redesignate or convert it according to RBI regulations, and the tax treatment may also change. Applicants should check the latest RBI guidance and consult their bank when their residential status changes.
Repatriation means transferring money from India to another country.
An NRE account offers one of the easiest repatriation facilities available to NRIs because:
This makes an NRE account particularly suitable for individuals who expect to move funds between India and their country of residence regularly.
Example: If you receive your salary in the UK and transfer part of it to your NRE account in India, you can later remit those funds back to your UK bank account, subject to applicable banking procedures and regulations.
Stop worrying about delays. Apply now and get your NRE Account Opening on time with our expert service.
The exact documentation may vary slightly by bank, but applicants are commonly asked to provide:
| Document | Purpose |
|---|---|
| Valid Passport | Identity verification |
| Valid Visa, Residence Permit, or Overseas Address Proof | Proof of NRI status |
| Passport-size Photograph | Account records |
| PAN Card (if applicable) | Tax compliance |
| Overseas Address Proof | Communication and KYC |
| Indian Address Proof (if available) | Additional verification |
Some banks may request additional KYC documents or require in-person or video verification. Always check the latest requirements with your chosen bank before applying.
Choosing between an NRE and an NRO account depends primarily on the source of your income and how you intend to use the funds.
| Feature | NRE Account | NRO Account |
|---|---|---|
| Primary Purpose | Manage foreign earnings | Manage income earned in India |
| Deposit Source | Foreign income | Indian and foreign income (as permitted) |
| Currency | Indian Rupees (INR) | Indian Rupees (INR) |
| Interest Taxation | Generally tax-exempt in India for eligible NRIs | Generally taxable in India |
| Repatriation | Principal and interest are generally fully repatriable | Repatriation is subject to applicable FEMA limits and conditions |
If you're unsure which account best suits your needs, read our detailed guide on NRE vs NRO Account for a comprehensive comparison.
Quick Tip: Many NRIs maintain both an NRE account for overseas earnings and an NRO account for income generated in India, such as rent, dividends, or pension.
Opening and managing an NRE account is straightforward, but avoiding these common mistakes can help you stay compliant with RBI and FEMA regulations.
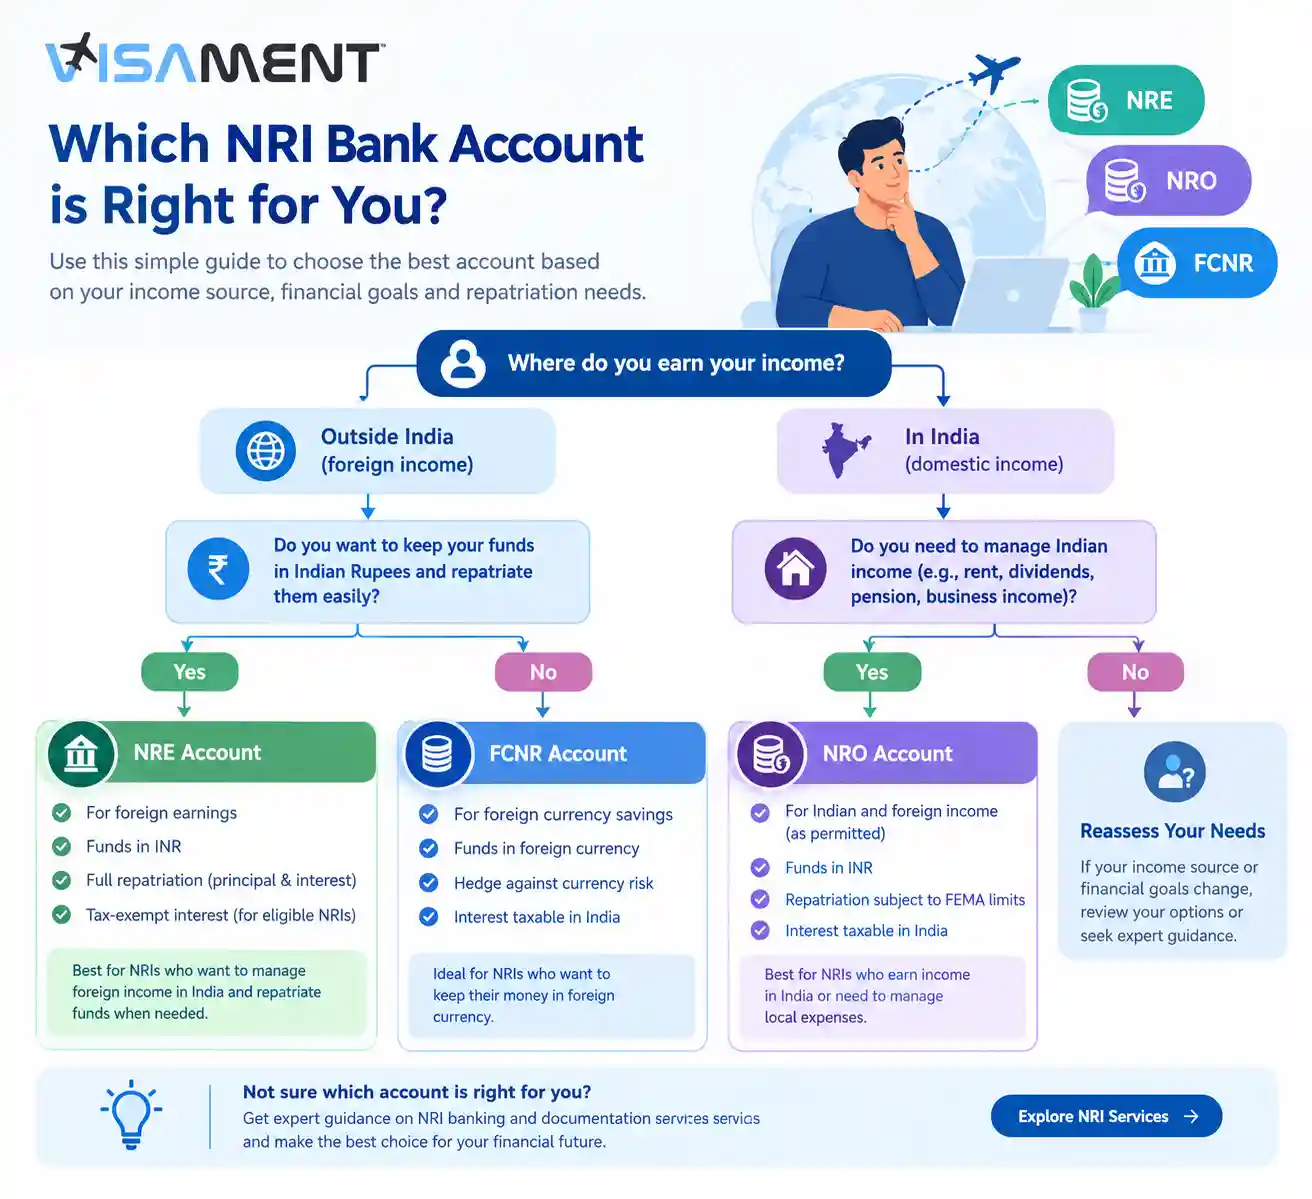
Understanding the purpose of each NRI account can help you choose the right banking solution and avoid unnecessary compliance issues.
Choosing the right NRI bank account depends on your source of income, investment plans, and repatriation needs. If you're unsure whether an NRE, NRO, or FCNR account is the best fit, professional guidance can help you make an informed decision.
If you're also managing NRI documentation, PAN, OCI, or other India-related financial services, consider consulting a trusted advisor to ensure your banking and documentation remain compliant with the latest regulations.
An NRE account is one of the most useful banking options for Non-Resident Indians who want to manage their overseas earnings in India. It allows eligible NRIs to hold foreign income in Indian Rupees, enjoy the benefit of repatriating funds abroad, and, in many cases, earn tax-exempt interest in India while maintaining their non-resident status.
Before opening an account, verify the latest eligibility criteria, documentation requirements, and regulatory provisions with your chosen bank and refer to the current RBI and FEMA guidelines. If you also earn income within India, consider whether you may need an NRO account alongside your NRE account for efficient financial management.
No. An NRE account is intended only for Non-Resident Indians (NRIs) and eligible Persons of Indian Origin (PIOs)/Overseas Citizens of India (OCIs) who reside outside India. If your residential status changes and you become a resident in India, the account generally needs to be redesignated according to RBI regulations.
Yes. Two or more eligible NRIs or PIOs/OCIs can jointly hold an NRE account. RBI also permits NRIs to hold an NRE account jointly with a resident close relative on a "former or survivor" basis, subject to the applicable conditions.
Yes. An NRE account is specifically designed to receive foreign earnings, including salary, business income, savings, and other eligible remittances received from outside India through approved banking channels.
Yes. Banks generally allow transfers from an NRE account to an NRO account, subject to applicable banking procedures and RBI regulations. However, transferring funds from an NRO account back to an NRE account is governed by separate FEMA rules and conditions.
When you permanently return to India or your residential status changes under FEMA, you generally cannot continue operating the account as an NRE account. The bank will redesignate or convert the account into the appropriate resident account, such as a Resident Rupee Account or, where eligible, a Resident Foreign Currency (RFC) Account.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.

When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.