Related Blogs

Managing your finances after moving abroad involves more than updating your address. If you've become a Non-Resident Indian (NRI), you may also need to change how you bank in India. Many NRIs are unsure whether they can continue using their resident savings account or which NRI account best suits their needs.
This guide explains what an NRI bank account is, who needs one, the different account types available, and how to choose the right option based on your income, financial goals, and banking requirements.
An NRI Bank Account is a specialized bank account that allows Non-Resident Indians (NRIs) to legally manage money in India after moving overseas. These accounts are governed by the Reserve Bank of India (RBI) under the Foreign Exchange Management Act (FEMA) and are designed to accommodate different sources of income and currency requirements.
Unlike a regular resident savings account, an NRI account helps you receive, hold, transfer, and manage funds according to your residential status. Depending on where your income comes from and how you intend to use your money, you can choose from three types of NRI accounts:
Each account serves a specific purpose, making it important to select the one that aligns with your financial needs.
When your residential status changes from resident to non-resident under FEMA, your banking arrangements should also reflect that change. Continuing to use a resident savings account after becoming an NRI may not comply with applicable banking regulations.
An NRI account helps you:
For example, if you work in Canada and regularly transfer part of your salary to India, an NRE account may be appropriate. On the other hand, if you earn rental income from a property in India, an NRO account is generally used to receive that income.
Note: Banking and regulatory requirements can change over time. Always verify the latest guidance with your bank and the Reserve Bank of India before opening or converting an account.
An NRI bank account is beneficial for individuals whose residential status falls under the non-resident category as defined by FEMA and who wish to maintain financial relationships in India.
You may need an NRI account if you:
Yes, many banks allow Overseas Citizen of India (OCI) cardholders who meet the applicable eligibility requirements to open NRI bank accounts. Individual banks may have specific documentation and KYC requirements, so it's important to confirm the latest eligibility criteria before applying.
If you become an NRI, you should inform your bank about your change in residential status. In most cases, your existing resident savings account should be redesignated or converted into an appropriate NRI account instead of continuing to operate as a resident account.
This helps ensure that your banking activities remain aligned with current RBI and FEMA regulations.
|
Situation |
Recommended Account (Overview) |
|---|---|
|
Salary earned abroad |
NRE Account |
|
Rental income from property in India |
NRO Account |
|
Pension received in India |
NRO Account |
|
Foreign currency fixed deposits |
FCNR Account |
|
Overseas savings transferred to India |
NRE Account |
The right choice depends on the source of your funds, whether you need to repatriate money overseas, and your long-term financial objectives.
In the next section, we'll explore the three main types of NRI bank accounts—NRE, NRO, and FCNR—and explain when each one is the most suitable option.
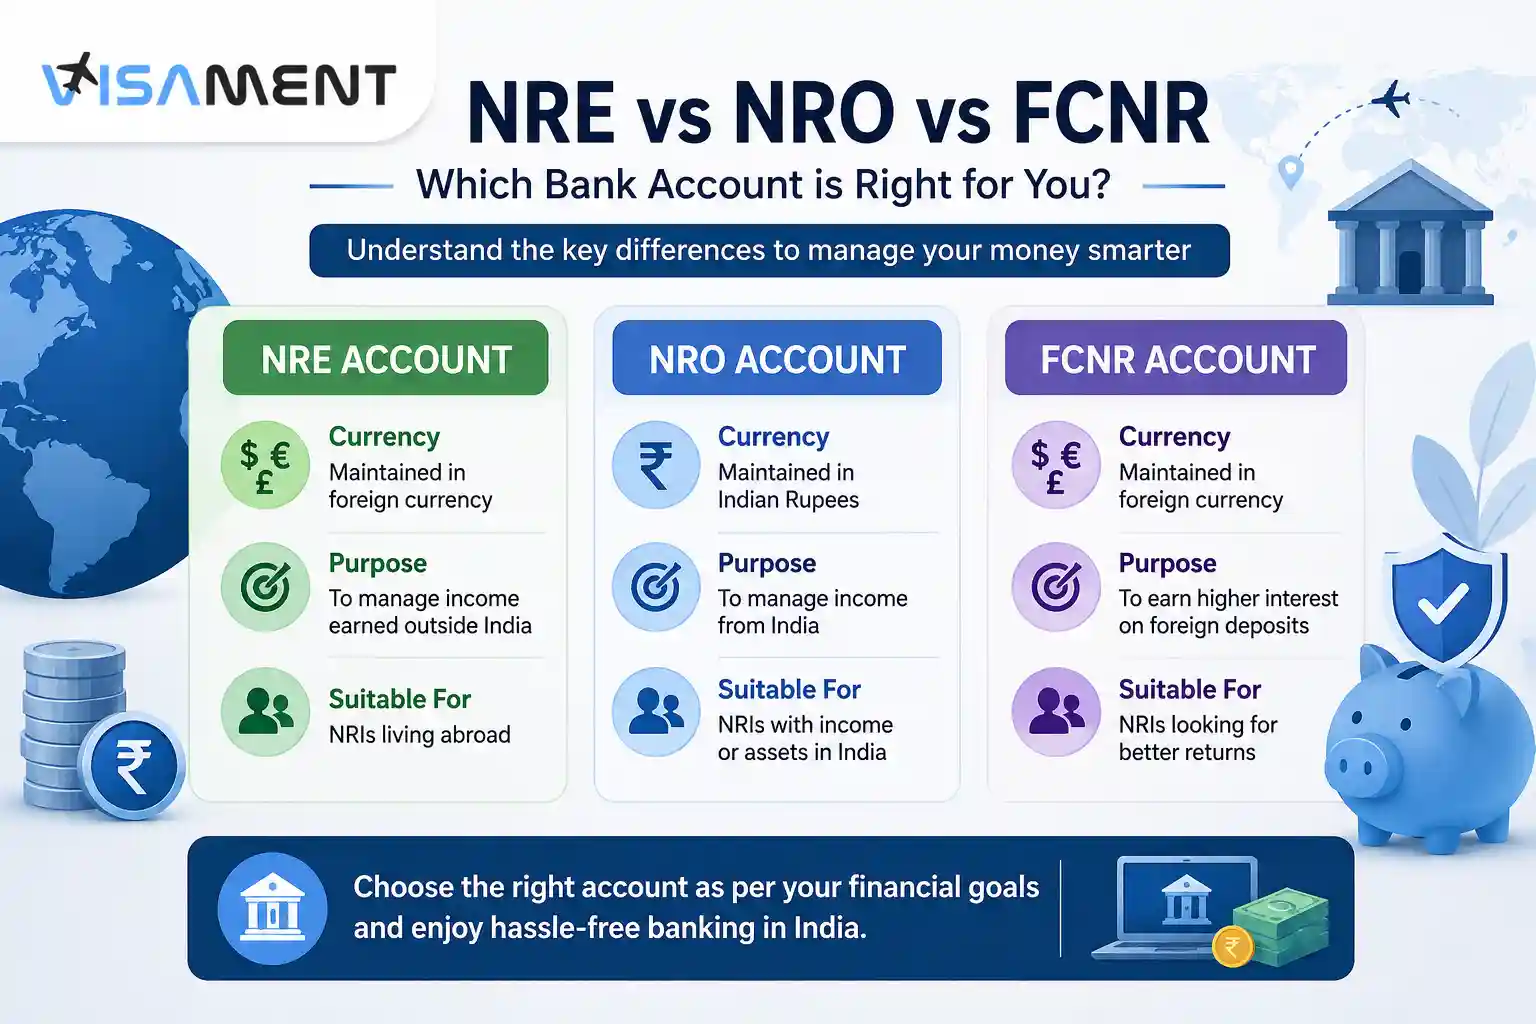
Choosing the right NRI bank account depends on where your money comes from, how you plan to use it, and whether you need to transfer funds abroad. The Reserve Bank of India (RBI) permits three primary types of NRI bank accounts:
Each account has a distinct purpose, so understanding their differences can help you make an informed decision.
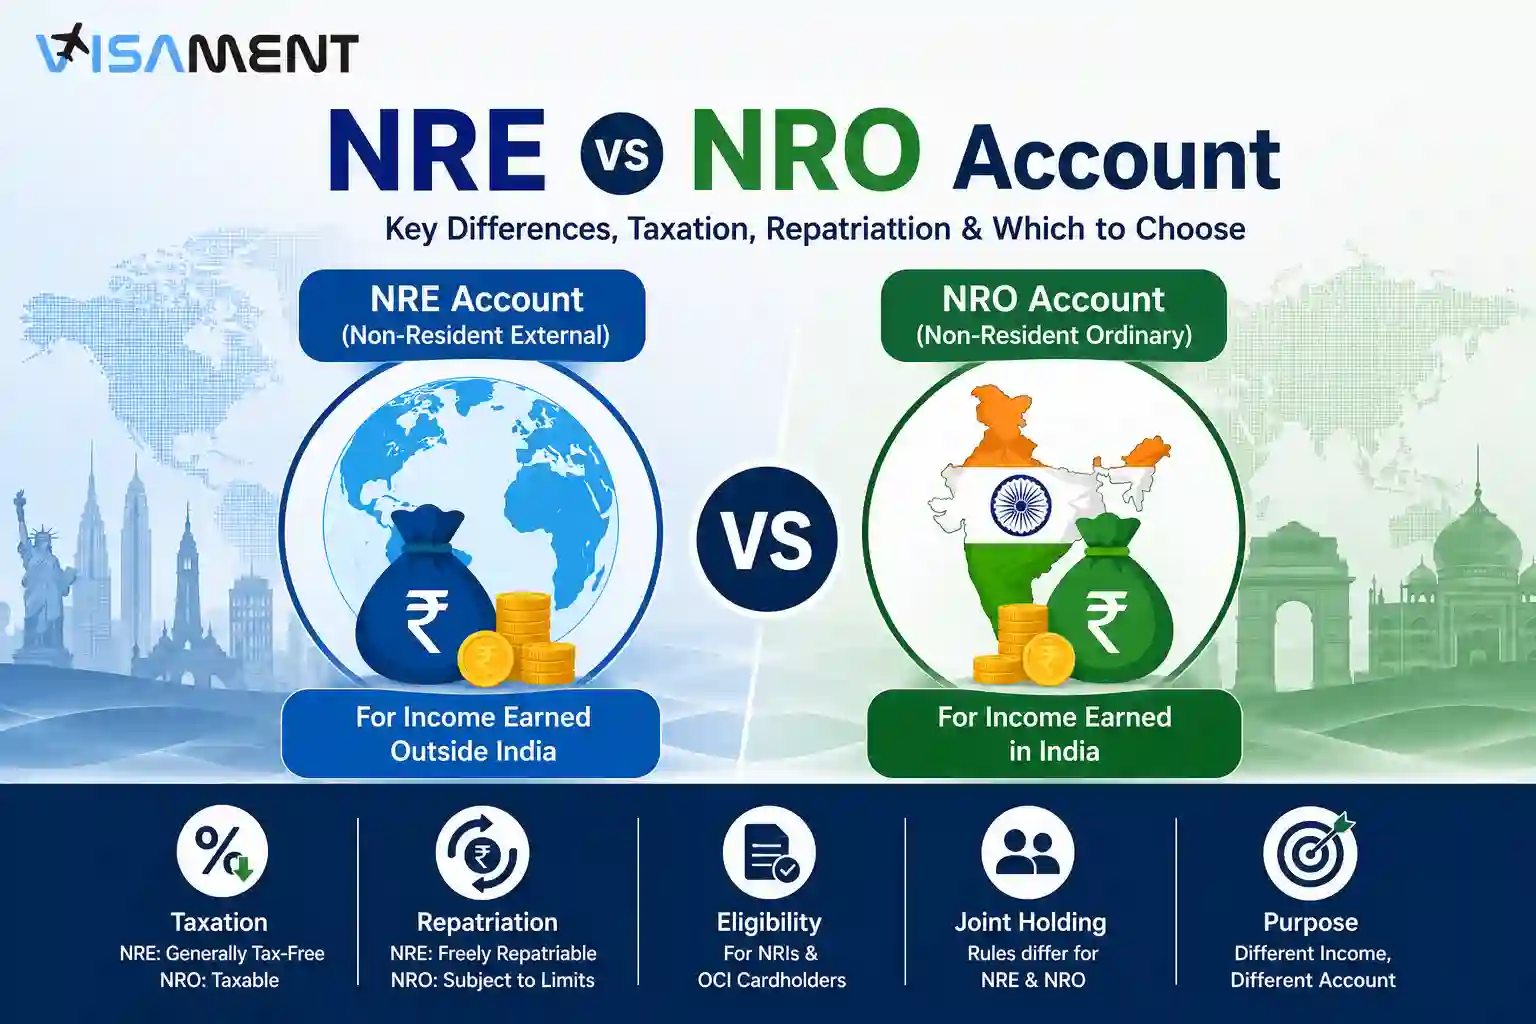
An NRE Account is designed for NRIs who want to deposit and manage income earned outside India. It allows you to hold your overseas earnings in Indian Rupees while making it easier to transfer money back to your country of residence, subject to applicable regulations.
An NRE account is generally suitable if you:
Example:
If you work in Australia and transfer part of your monthly salary to India for savings or investments, an NRE account is typically the most suitable option.
For detailed eligibility, taxation, and features, refer to your dedicated NRE Account Guide.
An NRO Account is intended for managing income that originates in India. It enables NRIs to receive and manage domestic earnings while maintaining compliance with Indian banking regulations.
An NRO account is commonly used for:
Example:
Suppose you relocate to the United Kingdom but continue receiving monthly rent from your apartment in Mumbai. In that case, an NRO account is generally used to receive and manage those payments.
If you want detailed information about taxation, repatriation, and account usage, link to your dedicated NRO Account Guide.
An FCNR Account is a fixed deposit account that allows NRIs to maintain deposits in designated foreign currencies instead of converting them into Indian Rupees.
This account is particularly useful for NRIs who want to reduce exposure to exchange rate fluctuations while earning interest on fixed deposits.
An FCNR account is best suited for individuals who:
Example:
An NRI earning in US Dollars who wishes to preserve savings in the same currency while earning interest may consider an FCNR deposit.
For currency options, deposit tenure, and other details, refer to the dedicated FCNR Account Guide.
Choosing the right account becomes easier when you compare their primary features side by side.
|
Feature |
NRE Account |
NRO Account |
FCNR Account |
|---|---|---|---|
|
Purpose |
Manage foreign earnings |
Manage income earned in India |
Hold foreign currency fixed deposits |
|
Currency |
Indian Rupees (INR) |
Indian Rupees (INR) |
Designated foreign currencies |
|
Primary Source of Funds |
Overseas income |
Income earned in India |
Foreign earnings |
|
Suitable For |
Salary, overseas savings, remittances |
Rent, pension, dividends, Indian income |
Long-term foreign currency savings |
|
Repatriation |
Generally freely repatriable |
Subject to RBI/FEMA regulations |
Generally repatriable |
|
Tax Treatment |
Depends on prevailing tax laws |
Depends on prevailing tax laws |
Depends on prevailing tax laws |
Note: Taxation, repatriation, and account regulations are subject to current RBI, FEMA, and Income Tax rules. Always verify the latest guidance before making financial decisions.
The answer depends on your financial situation rather than a single "best" account.
The next section explains who is eligible to open an NRI bank account, the documents typically required, and the account opening process.
Opening an NRI bank account is generally straightforward if you meet the eligibility criteria and provide the required Know Your Customer (KYC) documents. While documentation may vary slightly between banks, most follow the guidelines issued by the Reserve Bank of India (RBI).
You can typically apply for an NRI bank account if you:
If your residential status has changed from resident to non-resident, you should inform your bank and convert your existing resident account into the appropriate NRI account.
Although exact requirements vary by bank, applicants are generally asked to provide:
Some banks may request additional documents based on your country of residence or individual circumstances.
Note: Before applying, check your bank's latest documentation requirements, as KYC rules and compliance procedures may change over time.
Have questions? Our experts guide you through every step of the NRE Bank Account Services – no confusion, no delays.
Consult an Expert TodayMost Indian banks now allow eligible applicants to begin the account opening process online, making it easier for NRIs to complete much of the procedure from abroad.
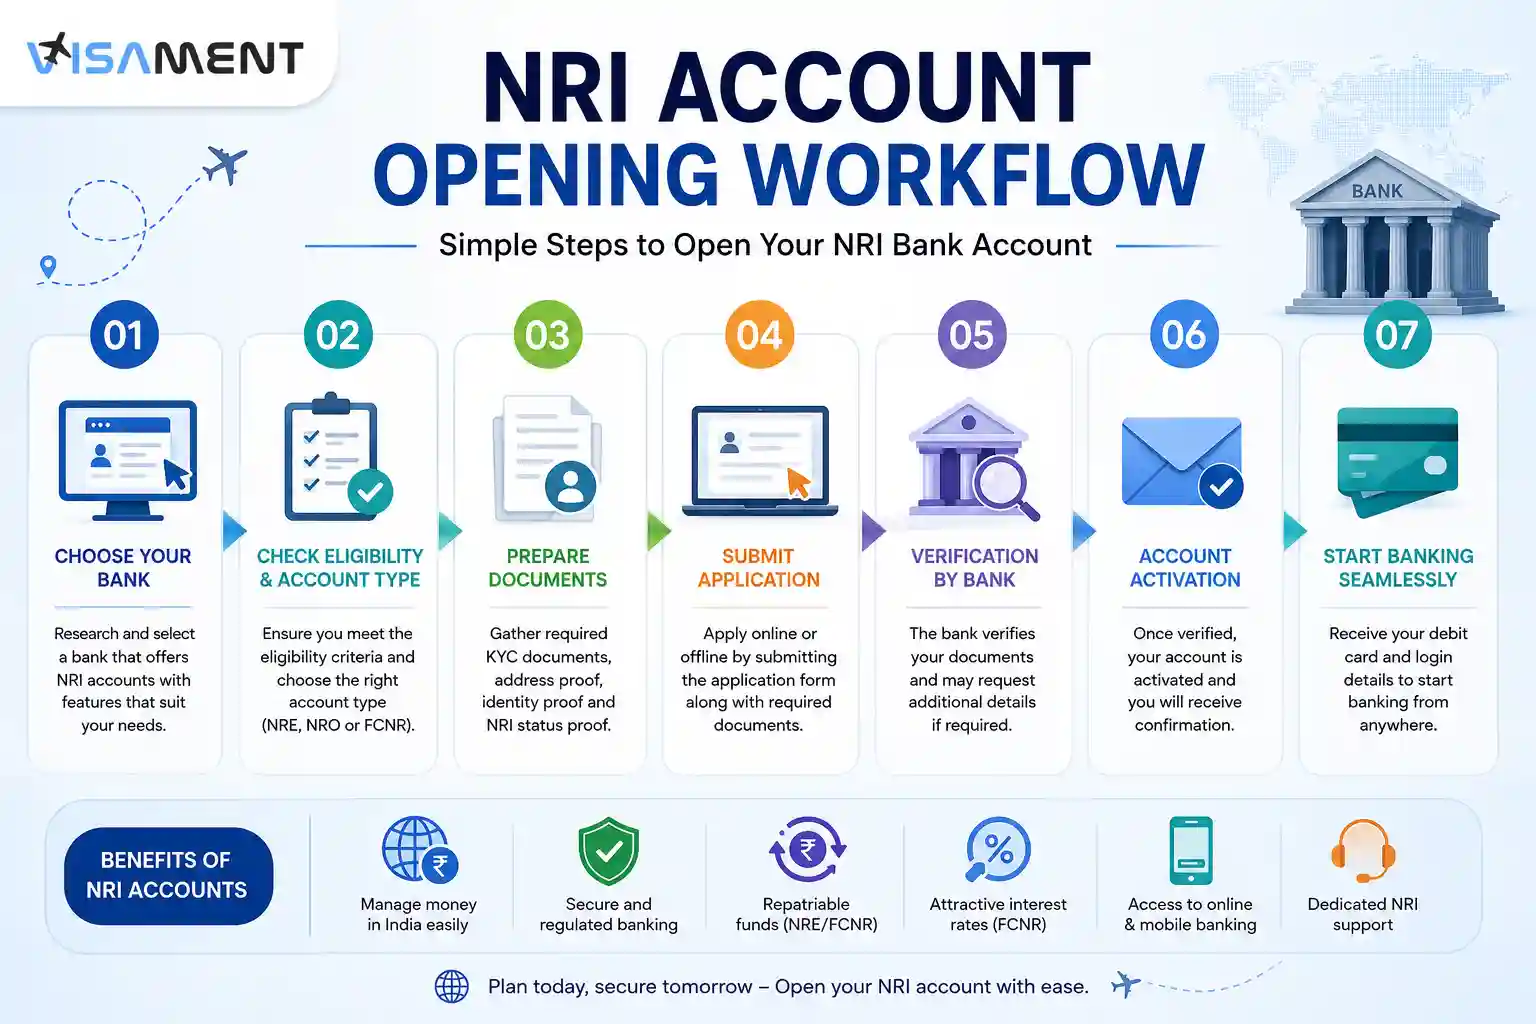
The general process usually involves the following steps:
Decide whether an NRE, NRO, or FCNR account best matches your financial needs.
Your decision should depend on:
Fill out the bank's NRI account opening form online or at an authorized branch.
Ensure that all personal details match your supporting documents to avoid delays.
Upload or submit the required KYC documents.
Depending on the bank, document verification may be completed:
The bank verifies your identity, residential status, and supporting documents before approving the application.
Additional verification may be required in certain cases.
Once verification is complete, your NRI account is activated.
You can then:
For a detailed walkthrough, application methods, and bank-specific procedures, link to your dedicated How to Open an NRI Bank Account guide.
There is no single "best" NRI bank account for everyone. The right choice depends on your income source, financial goals, and how you plan to use the account.
The table below can help you decide.
|
If you... |
Recommended Account |
|---|---|
|
Earn a salary abroad |
NRE Account |
|
Receive rental income in India |
NRO Account |
|
Receive pension or dividends in India |
NRO Account |
|
Want to keep fixed deposits in foreign currency |
FCNR Account |
|
Have both overseas income and Indian income |
NRE + NRO Accounts |
The most important consideration is where your money originates.
If you prefer to maintain savings in foreign currency and reduce exchange rate exposure, an FCNR Account may be more suitable than a standard rupee account.
If you regularly transfer funds back to your country of residence, consider the applicable repatriation rules for each account type before making a decision.
If you plan to invest in India while living abroad, choosing the appropriate account can make it easier to manage investments, savings, and future transactions.
Choose an NRE Account if your primary goal is managing overseas earnings in India.
Choose an NRO Account if your main objective is receiving and managing income generated within India.
Choose an FCNR Account if you want to hold long-term savings in designated foreign currencies without converting them into Indian Rupees.
Many NRIs find that maintaining both NRE and NRO accounts provides the flexibility to manage different income sources efficiently.
Choosing between an NRE, NRO, and FCNR account can be confusing, especially if you have multiple income sources or investment plans.
If you need personalized guidance, consider speaking with an NRI banking or documentation specialist who can help you understand the available options, documentation requirements, and account opening process based on your individual circumstances.
Choosing the right NRI account is only part of the process. Avoiding common banking mistakes can help you stay compliant with Indian regulations and manage your finances more efficiently.
One of the most common mistakes is continuing to operate a regular resident savings account after becoming an NRI. Once your residential status changes under FEMA, you should notify your bank and convert your account to the appropriate NRI category.
An NRE account is primarily meant for eligible foreign earnings. Income generated in India—such as rent, pension, dividends, or interest—should generally be credited to an NRO account in accordance with applicable banking regulations.
Selecting an account without considering your financial needs can create unnecessary complications.
For example:
Tax treatment and fund repatriation differ between NRE, NRO, and FCNR accounts. Before transferring funds or making investment decisions, understand the applicable rules or consult your bank or a qualified tax professional.
Banks periodically require customers to update their KYC records. Keeping your passport, overseas address, contact information, and other documents current helps prevent interruptions in banking services.
An NRI bank account is an essential financial tool for Non-Resident Indians who want to manage their money in India while complying with RBI and FEMA regulations. Whether you need an NRE account for overseas earnings, an NRO account for income generated in India, or an FCNR account for foreign currency fixed deposits, choosing the right account depends on your financial goals and the source of your funds.
Before opening an account, understand the differences between each account type, review the eligibility requirements, and verify the latest banking guidelines with your chosen bank. Making the right choice from the beginning can simplify banking, investments, and money transfers while helping you stay compliant with Indian regulations.
Yes. Many NRIs maintain both accounts because they serve different purposes. An NRE account is commonly used for foreign earnings, while an NRO account is used for income earned in India.
Many Indian banks allow eligible OCI cardholders to open NRI accounts, subject to RBI guidelines and the bank's documentation requirements.
If your primary income is earned outside India, an NRE account is generally the most suitable option for managing those funds in India.
Rental income earned from property in India is generally credited to an NRO account.
Many Indian banks offer online account opening or allow applicants to begin the process digitally. The exact procedure and verification requirements vary from one bank to another.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.
When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.