Related Blogs

If you live outside India but continue to receive income or manage financial assets in India, you may need an account designed for non-resident banking. A Non-Resident Ordinary (NRO) Bank Account allows eligible non-residents to manage permitted Indian-rupee transactions and income. This guide explains who can use an NRO account, what it is used for, how taxation and repatriation work, and how it differs from an NRE account.
A Non-Resident Ordinary (NRO) Bank Account is an Indian-rupee account that a person resident outside India can use for permitted rupee transactions in India under applicable foreign-exchange rules. The Reserve Bank of India (RBI) recognizes NRO accounts as one of the principal account types available to non-residents.
An NRO account can be useful when an NRI continues to have financial obligations or income in India. For example, an NRI who owns a property in India may receive rental income, while another person may receive a pension, dividend or other legitimate income in India.
Unlike an NRE account, an NRO account is particularly relevant for managing eligible Indian-source income and rupee transactions.
An NRO (Non-Resident Ordinary) Bank Account can generally be opened by a person residing outside India to manage permitted Indian rupee transactions and income.
In simple terms: An NRO account is designed for eligible non-residents who need to receive, hold, and manage permitted income and payments in India.
 Also Want to Know About SBI NRI Account Check Now!
An NRO account is primarily useful for managing permitted Indian-rupee income and expenses while living outside India.
Common examples include:
For example, suppose an NRI living in the United States owns an apartment in India and receives rent from the property. An NRO account can provide a mechanism for receiving and managing that Indian income, subject to applicable tax and banking rules.
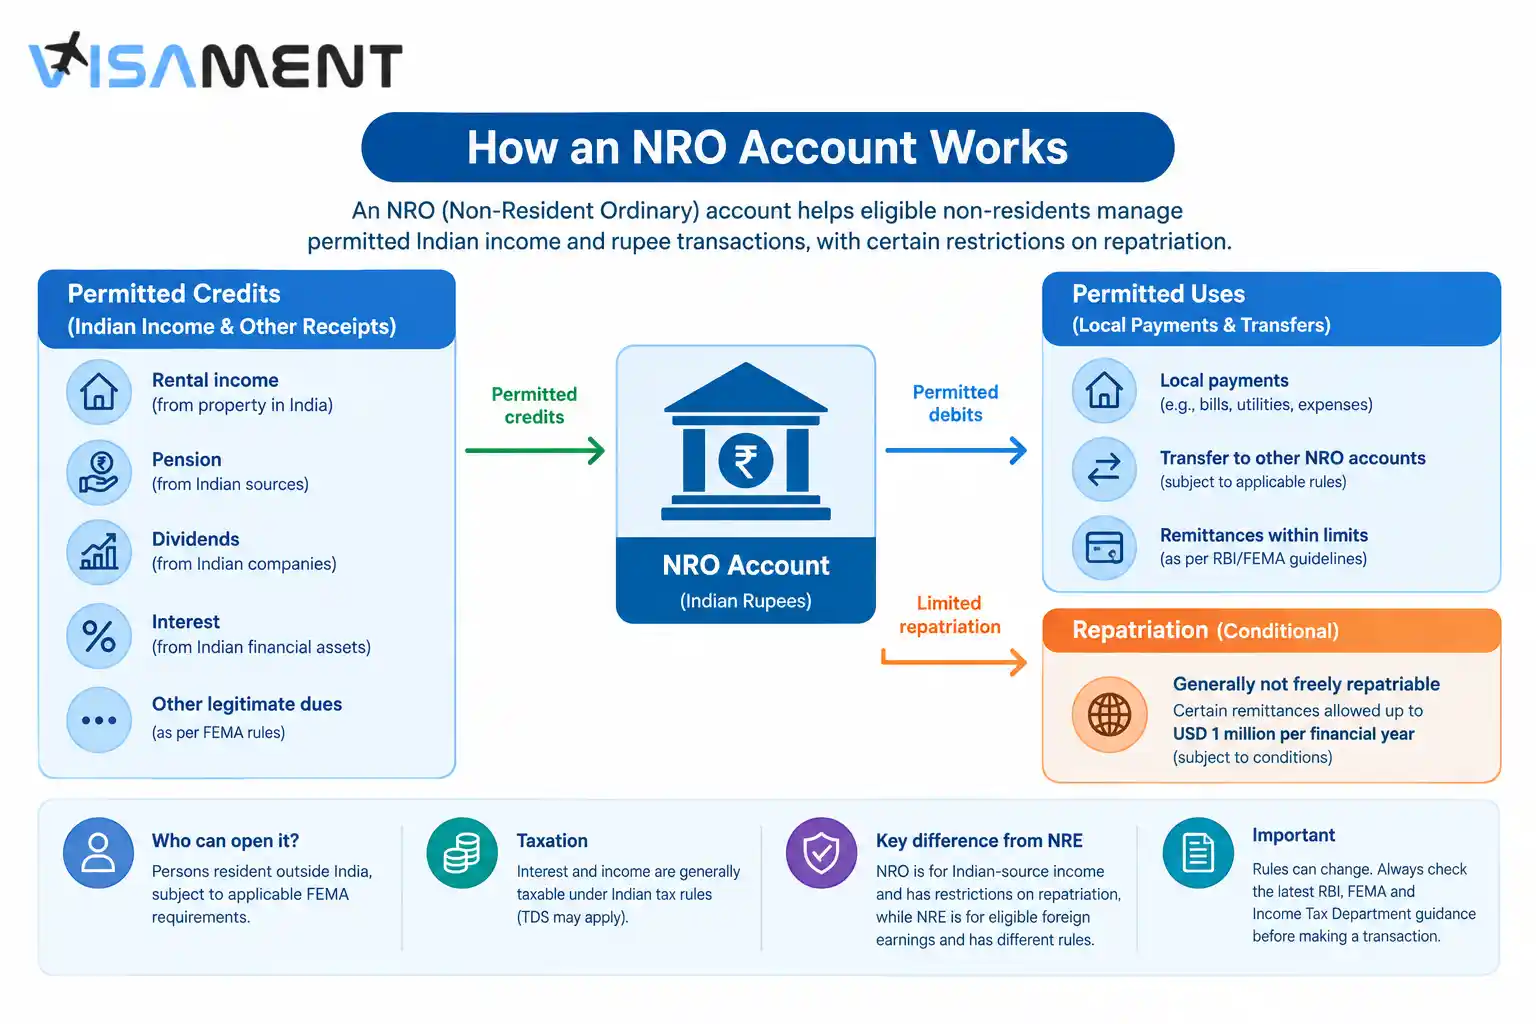
The RBI permits specified legitimate dues in India and other permitted credits to an NRO account.
Also Want to Know About How NRIs can Open an NRE and NRO Account in India? Check Now!Permitted credits to an NRO account can include legitimate dues in India and other transactions allowed under applicable regulations. Depending on the circumstances, permitted credits can also include transfers from other NRO accounts and certain inward remittances.
The important point is that not every type of foreign or domestic transaction can automatically be credited to an NRO account. The source and nature of the funds matter.
For a specific transaction, the account holder should check the applicable RBI/FEMA rules and the requirements of the authorised dealer bank.
NRO funds can generally be used for permitted local payments and other transactions allowed under the applicable rules.
The RBI identifies local disbursements, transfers to other NRO accounts and certain remittances as permissible debits.
However, using money in India and transferring money outside India are not the same thing. Repatriation of NRO funds is subject to specific conditions and limits, which should be checked before making an overseas transfer.
Also want to know about NRO Account Repatriation Rules Check Now!Yes. Income from an NRO account is generally taxable in India under the applicable tax rules. The exact tax treatment, withholding requirements and filing obligations depend on the type of income and the taxpayer's circumstances.
The NRO account itself should therefore not be treated as a tax-free account. This is an important distinction when comparing NRO and NRE accounts.
Tax rules are also subject to legislative changes. India's Income Tax Act, 2025 applies prospectively to tax years beginning on or after April 1, 2026, so tax-related information should be verified against the current Income Tax Department guidance before publication or filing.
For detailed NRO taxation, TDS or income-tax filing questions, a separate tax-focused guide is more appropriate.
NRO balances are generally not freely repatriable outside India. However, eligible NRIs and PIOs can remit certain amounts subject to applicable conditions.
The RBI currently states that NRO balances of NRIs/PIOs can be remitted up to USD 1 million per financial year (April–March) along with other eligible assets, subject to the conditions under the applicable foreign-exchange regulations.
Current income may also be remitted abroad subject to the applicable rules. An NRI may also transfer eligible funds from an NRO account to an NRE account within the applicable USD 1 million facility and subject to tax and other conditions.
Because documentation, tax compliance and the nature of the funds can affect a remittance, anyone planning a significant transfer should confirm the current requirements with their authorised dealer bank.
When a person who maintains an Indian resident bank account becomes a non-resident under FEMA, the existing resident account generally needs to be redesignated as an NRO account.
This is particularly relevant for Indians moving abroad for employment, business, vocation or with an intention to stay outside India. RBI guidance provides for redesignation of the existing account as NRO in such circumstances.
The account holder should notify the bank and complete the required KYC and status-update formalities rather than continuing to treat the account as an ordinary resident account.
Before opening or using an NRO account, check:
Rules relating to foreign exchange and taxation can change, so current RBI, FEMA and Income Tax Department guidance should be checked for transactions involving significant amounts.
Stop worrying about delays. Apply now and get Indian Counsellor Services.
Chat NowA Non-Resident Ordinary (NRO) Bank Account is primarily designed to help eligible non-residents manage permitted Indian-rupee transactions and income in India. It can be useful for handling rental income, pension, dividends and other legitimate Indian dues, but taxation and repatriation rules make it different from an NRE account.
If you are changing your residential status, receiving Indian income or planning to transfer NRO funds abroad, check the current RBI/FEMA and Income Tax Department requirements before completing the transaction.
Yes, NRIs can transfer money to an NRO account via international wire transfers or remittance services. The amount is converted into Indian Rupees (INR) upon deposit.
Yes, but once you attain NRI status, you must convert your resident savings account into an NRO account as per FEMA rules before making transfers.
Yes, you can transfer money from an NRO account to a resident savings account in India. However, NRIs cannot hold a resident savings account and must use an NRO account instead.
Yes, NRIs in the USA can open an NRO account online by submitting documents digitally or via courier. Some banks offer video KYC for verification.
Yes, funds can be withdrawn in Indian Rupees (INR) from an NRO account at any ATM or bank branch in India.
NRIs, PIOs, and OCIs can open an NRO account to manage income earned in India, such as rent, dividends, or pensions.
Depends on the NRIs requirements.
Yes, but once transferred, it cannot be reversed. Use an NRO account for managing Indian earnings and an NRE account for foreign income with repatriation benefits.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.
Top NRI Investment Options Available in India: Best Plans for 2026
NRI Bank Account: Types, Benefits, Eligibility & How to Choose
Difference Between an NRE and NRO Account: Tax & Eligibility
Understanding FCNR Account: Features, Eligibility & Benefits
What Is an NRE Account? Benefits, Rules & Opening Process

When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.