Related Blogs

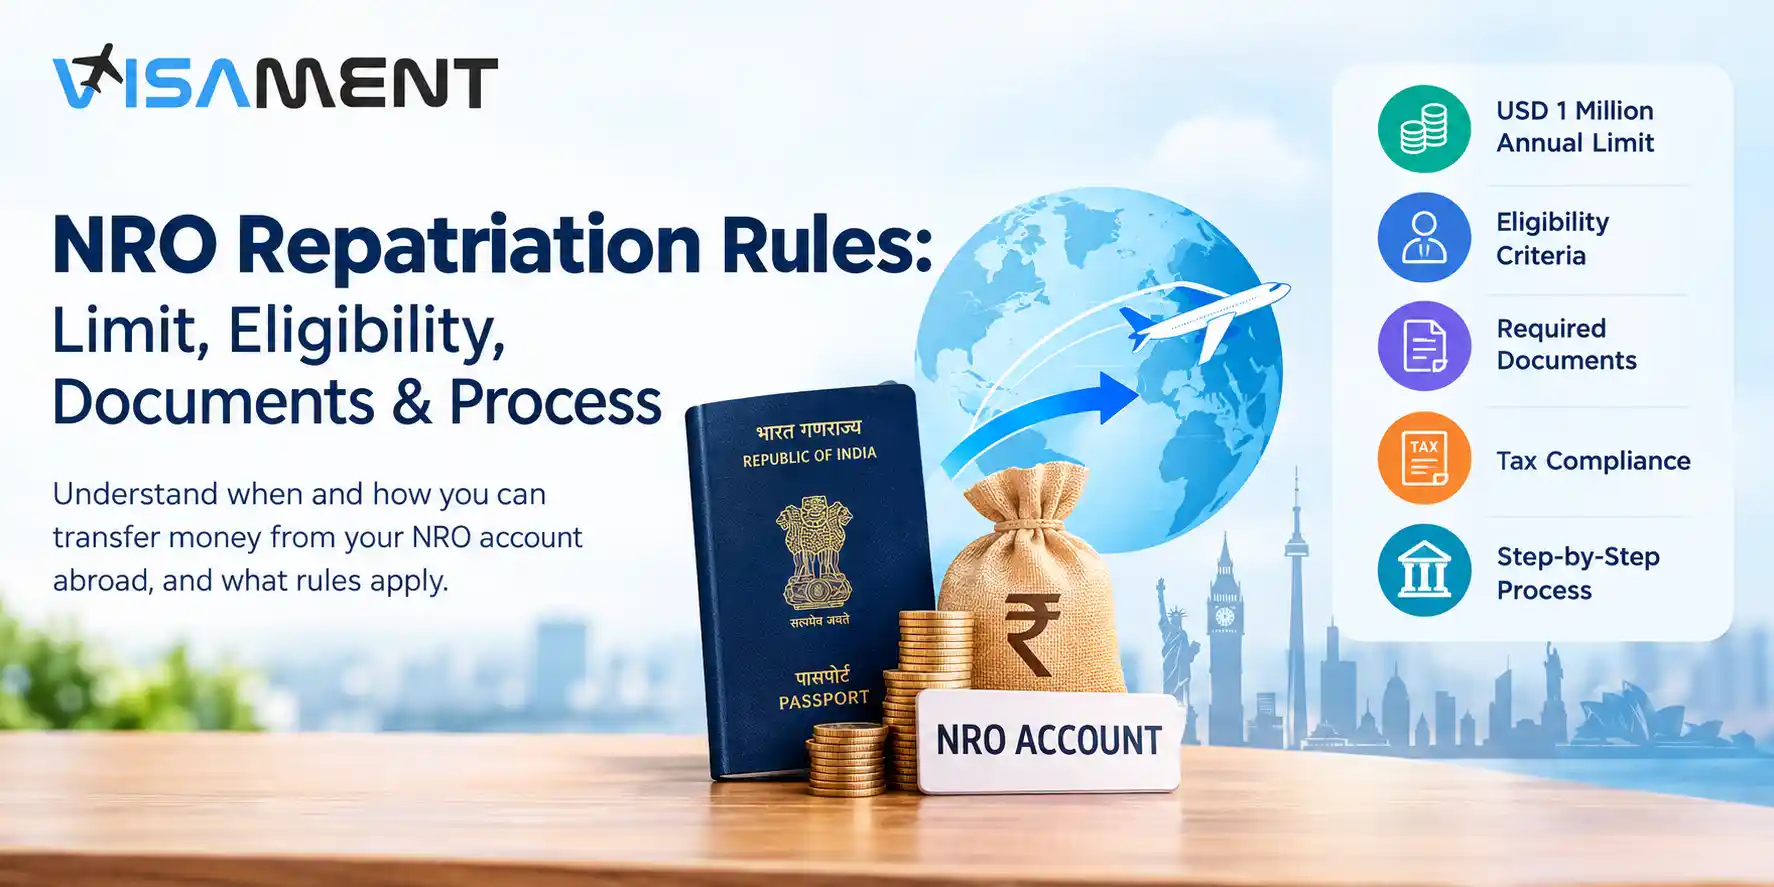
If you have money in an NRO account and want to transfer it outside India, the process is subject to specific FEMA and RBI rules. Eligible NRIs and PIOs can generally repatriate up to USD 1 million per financial year from eligible NRO balances and other qualifying assets, subject to applicable conditions and taxes.
This guide explains the NRO repatriation limit, what types of funds may be transferred, the documents and tax compliance that may apply, and how to approach the remittance through an Authorised Dealer bank.
Yes. Eligible NRIs and PIOs can repatriate qualifying money from an NRO account, but the balance is not generally freely repatriable like money in an NRE account. RBI guidance provides for repatriation of NRO balances by eligible NRIs and PIOs up to USD 1 million per financial year, subject to the conditions under the applicable FEMA framework. Funds can also be transferred to an NRE account within this USD 1 million facility.
The important point is that not every amount credited to an NRO account should automatically be treated in the same way. The source of the money matters.
For example, current income earned in India and accumulated balances or proceeds from assets may follow different regulatory and documentation requirements.
|
Account |
Broad repatriation position |
|---|---|
|
NRO |
Subject to FEMA conditions; eligible NRIs/PIOs can generally use the USD 1 million annual facility for qualifying balances/assets |
|
NRE |
Generally repatriable, subject to applicable rules |
|
Generally repatriable, subject to applicable rules |
The table is only a high-level comparison. The exact treatment depends on the transaction and source of funds.
 Also Want to Know About Fund Repatriation for NRIs Check Now!
The general facility for eligible NRIs and PIOs is up to USD 1 million per financial year, subject to the applicable FEMA conditions and payment of applicable taxes in India. RBI materials specify the financial year as April to March.
This should not be understood simply as a USD 1 million withdrawal limit from the bank account. It is a foreign-exchange repatriation facility governed by FEMA rules.
The USD 1 million framework can apply to qualifying balances in an NRO account and certain eligible asset proceeds, including specified proceeds connected with assets acquired through inheritance or other permitted routes.
For example, if an eligible NRI has qualifying funds that can be repatriated under the facility, the relevant amount must be considered together with any other applicable remittances using the same annual facility. The bank will determine the documentation and regulatory requirements for the particular transaction.
The source and nature of the funds are important when determining the applicable repatriation route.
Income such as rent, dividends, pension and interest can have separate remittance treatment. RBI guidance permits remittance of current income abroad, subject to applicable tax compliance and the bank's requirements.
Current income should therefore not automatically be treated as part of the same restriction that applies to repatriation of the underlying NRO balance.
Apart from current income, eligible NRIs and PIOs can generally repatriate qualifying NRO balances within the USD 1 million per financial year facility, subject to the applicable FEMA conditions, documentation and taxes.
Sale proceeds from qualifying assets in India can also fall within the applicable remittance-of-assets framework. Property transactions can involve additional FEMA conditions and supporting documents, so a property sale should not be treated as an ordinary bank-balance transfer.
Inherited or legacy assets can also have specific repatriation provisions. Documentary evidence establishing the inheritance or acquisition of the asset may be required, along with applicable tax compliance.
If the money originated from a property sale, inheritance, investment or another asset transaction, the supporting documentation should establish the source and ownership of the funds.
Also Want to Know About NRIs Returning to India from the USA Check Now!Before an NRO remittance is processed, the transaction generally needs to satisfy the applicable FEMA requirements and the Authorised Dealer bank's verification requirements.
Important considerations include:
The exact documentation should therefore be confirmed with the bank handling the remittance rather than copied from a generic checklist.
Also Want to Know About Fund Repatriation for NRIs Check Now!There is no single universal document list for every NRO repatriation transaction. Requirements can differ depending on whether the funds represent ordinary NRO savings, current income, property-sale proceeds, inheritance or another eligible asset.
Depending on the transaction, the bank may ask for:
For foreign remittances made on or after 1 April 2026, the Income Tax Department's current framework uses Form 145, which replaces the earlier Form 15CA, and Form 146, which replaces the earlier Form 15CB. The applicable requirements depend on the nature and taxability of the remittance.
This distinction is important because older NRO repatriation articles may still refer to Forms 15CA and 15CB as though they remain the current forms. Readers should verify the applicable forms under the law in force on the date of their remittance.
Also Want to Know About NRIs Returning to India From UAE Check Now!The practical process usually follows these stages:
Determine whether the amount represents current income, accumulated NRO funds, property-sale proceeds, inheritance or another type of asset.
Check whether the proposed transfer falls under the USD 1 million facility or another repatriation provision.
Determine whether the remittance has Indian tax implications and what reporting, deduction, NRI certificate or other compliance is required.
Collect evidence establishing the source, ownership and tax treatment of the funds. The exact documents depend on the transaction.
The bank reviews the request, documents, applicable FEMA conditions and tax compliance before processing the transfer.
Once the bank is satisfied that the applicable requirements have been met, it can process the remittance through the banking channel.
Property-sale proceeds and inherited assets can involve additional documentation and FEMA considerations.
For eligible NRIs and PIOs, RBI's remittance-of-assets framework covers qualifying balances in NRO accounts and certain proceeds from assets, including assets acquired through inheritance or legacy, within the applicable USD 1 million annual facility.
|
Situation |
What to consider |
|---|---|
|
Property sale |
Verify the applicable FEMA conditions, source of acquisition, sale documentation and tax compliance |
|
Inheritance/legacy |
Establish the inheritance or legacy through appropriate documentary evidence and satisfy applicable tax and FEMA requirements |
|
Ordinary NRO balance |
Check eligibility for the USD 1 million facility and provide evidence of the source of funds |
These situations can involve additional rules that are better handled separately from the general NRO repatriation process.
A remittance above the standard USD 1 million facility is not automatically permitted. RBI's remittance-of-assets guidance provides for prior RBI approval in specified circumstances where an NRI or PIO seeks to remit more than USD 1 million per financial year from qualifying NRO balances or eligible assets.
Therefore, an applicant should not simply instruct a bank to send an amount above the annual facility and assume that the standard NRO process will apply.
Where a transaction may exceed the applicable limit, the relevant FEMA provisions and RBI approval requirements should be checked before initiating the remittance.
The most important difference is repatriability.
An NRE account is generally designed for funds that can be repatriated outside India, subject to applicable rules. An NRO account is primarily used for managing income and legitimate financial transactions in India, with repatriation of balances subject to the applicable FEMA framework. RBI specifically states that eligible NRO balances can be repatriated up to USD 1 million per financial year and that funds can be transferred to an NRE account within this facility.
Before requesting an overseas transfer, check:
If the transaction involves property, inheritance or another significant asset, getting the documentation and tax position reviewed before submitting the remittance request can help avoid preventable delays or rework.
Stop worrying about delays. Apply now and get Indian Counsellor Services.
Chat NowNRO repatriation is possible for eligible NRIs and PIOs, but it is governed by FEMA conditions rather than being freely available in the same way as NRE funds. The standard facility is up to USD 1 million per financial year, while current income and specific transactions such as property sales or inheritance may have additional rules.
The safest approach is to identify the source of the funds first, verify the applicable FEMA and tax requirements, prepare supporting documents, and confirm the current process with the Authorised Dealer bank before initiating the transfer. Because both foreign-exchange and tax rules can change, current RBI and Income Tax Department guidance should be checked for the specific remittance date.
Eligible NRIs and PIOs can generally repatriate up to USD 1 million per financial year from qualifying NRO balances and eligible assets, subject to applicable FEMA conditions and tax compliance. The financial year runs from April through March.
Yes, eligible NRO funds can be remitted abroad when the transaction satisfies the applicable FEMA, tax and banking requirements. NRO balances are not generally freely repatriable without these conditions.
Yes. RBI guidance permits eligible funds to be transferred from an NRO account to an NRE account within the applicable USD 1 million per financial year facility, subject to the relevant conditions and tax compliance.
Potentially, subject to the applicable FEMA provisions, the nature of the property and acquisition, supporting documents, tax compliance and the applicable repatriation limit. Property-sale transactions should be reviewed separately where specific conditions apply.
Eligible inherited or legacy assets can fall within the remittance-of-assets framework. Documentary evidence supporting the inheritance or legacy and applicable tax compliance may be required.
For remittances made on or after 1 April 2026, the Income Tax Department states that Form 145 replaces Form 15CA and Form 146 replaces Form 15CB under the new tax framework. The precise reporting and certification requirements depend on the remittance.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.

When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.