Related Blogs

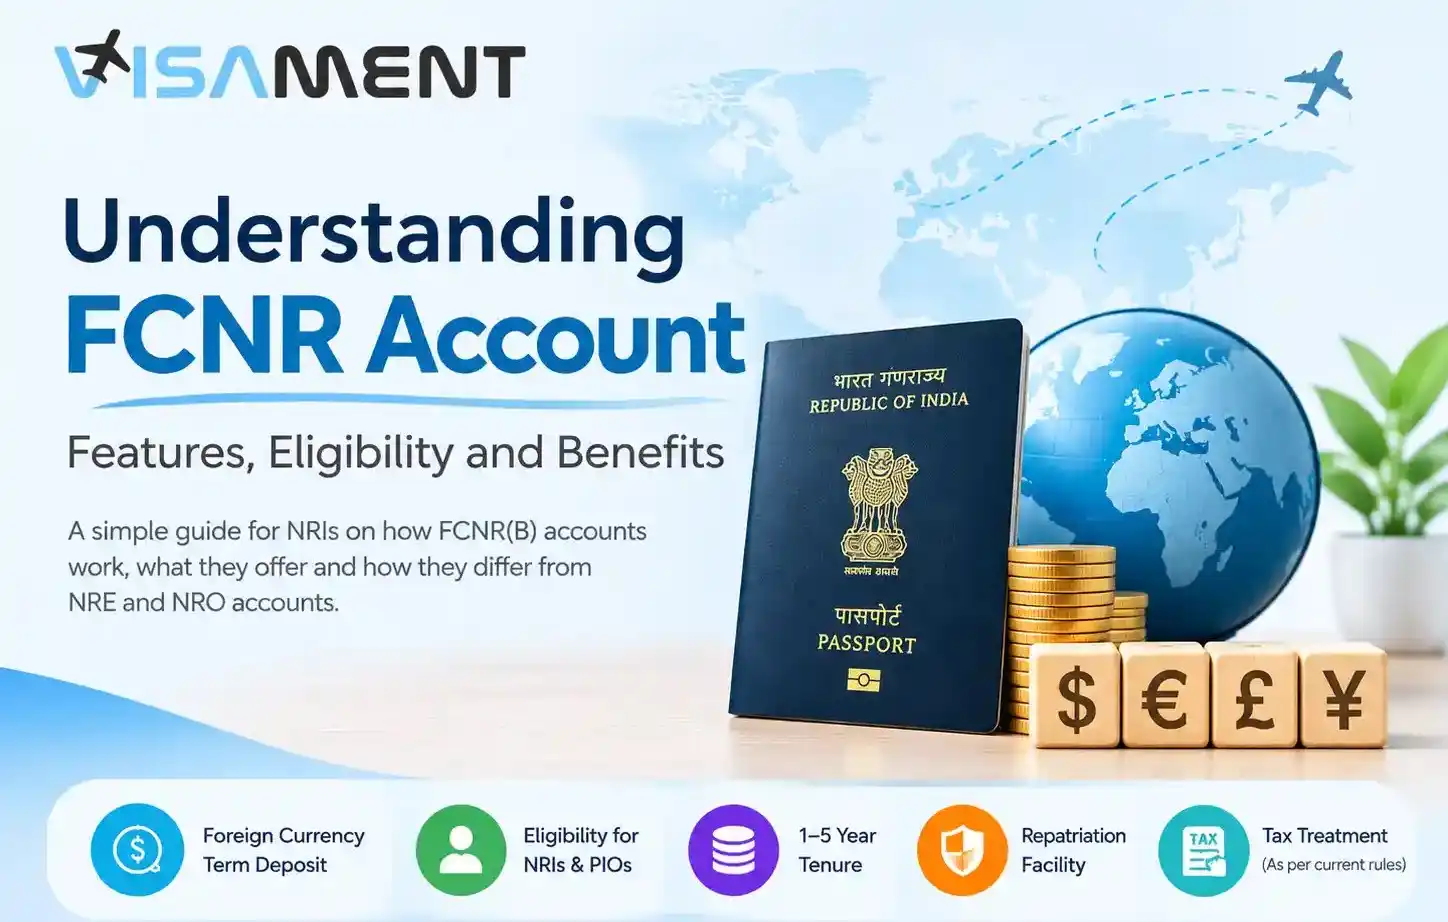
If you are an NRI holding savings in a foreign currency, you may want to keep those funds in that currency instead of converting them into Indian rupees. An FCNR(B) account is designed for this purpose. This guide explains what an FCNR account is, how it works, who can use it, its tenure and interest features, and how it differs from NRE and NRO accounts.
An FCNR(B) account is a foreign-currency term deposit for eligible non-residents. Unlike an NRE Account or NRO account, which is denominated in Indian rupees, an FCNR(B) deposit is maintained in a permitted foreign currency. RBI describes FCNR(B) as a term-deposit facility for eligible non-residents.
The account can be useful for an NRI who has foreign-currency savings and wants to place those funds in an Indian bank without first converting the principal into INR.
Because FCNR(B) is a term deposit, it is different from a regular savings account. The money is placed for a specified period and earns interest according to the terms offered by the bank and the applicable RBI framework.
The basic process is straightforward:
FCNR(B) deposits can be funded through permitted foreign-currency remittances and other transactions allowed under the applicable RBI framework. Transfers between certain NRE and FCNR(B) accounts of the same account holder are also permitted under RBI rules.
The important point is that the deposit remains foreign-currency denominated. This can matter to an NRI who expects to use the funds in the same foreign currency later.
FCNR(B) accounts are intended for eligible non-residents, including NRIs and eligible persons of Indian origin under the applicable rules. RBI's NRI banking guidance identifies FCNR(B) as an account that can be opened by NRIs and PIO/OCI categories.
Eligibility can depend on the individual's residential status and the circumstances under which the account is opened or maintained. Banks may also have their own documentation and onboarding requirements.
If you need detailed eligibility conditions or documentation, that information is better handled in a dedicated FCNR account eligibility guide rather than repeating every requirement here.
FCNR(B) deposits are maintained in freely convertible foreign currencies permitted under the applicable RBI framework.
Common currencies used for FCNR deposits include:
The exact currencies a bank accepts can vary, so an account holder should confirm the current list and the bank's available options before opening a deposit. RBI materials identify these currencies among those permitted for FCNR(B) deposits.
Keeping the deposit in a foreign currency can also reduce the need to immediately convert foreign savings into INR. However, this does not mean that currency movements are irrelevant to the account holder's overall financial position.
FCNR(B) deposits are term deposits with a minimum maturity of one year and a maximum maturity of five years. RBI rules specify maturity categories beginning at one year and state that banks cannot accept or renew FCNR(B) deposits beyond five years.
Interest rates are determined by individual banks within the applicable RBI regulatory framework. Rates can differ by:
Because interest-rate rules and benchmark rates can change, current FCNR rates should always be checked directly with the bank before making a deposit. RBI's current framework places ceilings on FCNR(B) deposit rates based on the relevant currency reference rate and maturity.
 Also, Want to Know About SBI NRI Account Check Now!
Tax treatment is an important consideration for NRIs. Indian income-tax guidance has changed with the transition to the Income-tax Act, 2025, which applies prospectively to tax years beginning on or after April 1, 2026.
The Income Tax Department has also specifically identified interest on Foreign Currency Non-Resident (FCNR) accounts as exempt from tax under the Income-tax Act, 1961 framework.
Because tax treatment depends on the applicable law, residential status and the relevant tax year, readers should verify the current Income Tax Department provisions before relying on an exemption for a particular situation.
For detailed tax rules, exemptions and reporting requirements, use a dedicated FCNR taxation guide rather than treating this introductory explanation as personalised tax advice.
FCNR, NRE and NRO account all serve non-resident banking needs, but they are structured differently.
|
Feature |
FCNR(B) |
NRE |
NRO |
|---|---|---|---|
|
Currency |
Foreign currency |
Indian rupee |
Indian rupee |
|
Basic structure |
Term deposit |
Savings/current/term deposit options |
Savings/current/term deposit options |
|
Main use |
Holding eligible foreign-currency deposits |
Managing repatriable rupee funds |
Managing income and funds connected with India |
|
Tenure |
1–5 years for FCNR(B) term deposits |
Bank/product dependent |
Bank/product dependent |
|
Currency conversion |
Deposit remains in designated foreign currency |
Funds are INR-denominated |
Funds are INR-denominated |
RBI's NRI guidance confirms that NRE and NRO accounts are rupee-denominated, while FCNR(B) is a foreign-currency term-deposit facility.
The right account depends on factors such as the currency in which you hold funds, how you expect to use the money, liquidity requirements and applicable tax and repatriation rules.
Before placing money in an FCNR deposit, consider:
An FCNR deposit can be useful for someone who wants a fixed-term foreign-currency deposit in India, but the account should be evaluated according to the individual's financial requirements rather than simply by its interest rate.
Stop worrying about delays. Apply now and get Indian Counsellor Services.
Chat NowAn FCNR(B) account is a foreign-currency term deposit designed for eligible non-residents. Its key features include foreign-currency denomination, one-to-five-year deposit periods, interest earnings and repatriation facilities under applicable rules.
For an NRI considering this type of deposit, the main points to evaluate are the currency, tenure, current bank rate, premature-withdrawal conditions, repatriation rules and applicable tax treatment. Always verify current terms with the bank and the relevant official authorities before opening or renewing an FCNR deposit.
Key benefits include foreign-currency deposits, protection from direct INR exchange-rate fluctuations on the principal, fixed-term returns, and repatriation facilities, subject to applicable RBI and bank rules.
The tax treatment of FCNR interest depends on the account holder's residential status and the applicable tax law. NRIs should check the current Income Tax rules or consult a qualified tax professional.
FCNR(B) deposits generally have a tenure of 1 to 5 years. The exact interest rate offered depends on the bank, currency, and deposit tenure.
Eligible Non-Resident Indians (NRIs) and Persons of Indian Origin (PIOs) can open an FCNR(B) account with an authorized bank in India, subject to applicable RBI rules.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.

When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.