Related Blogs

Buying property in India while living abroad can feel overwhelming, especially when you need to comply with Indian regulations, arrange finances from overseas, and complete legal formalities remotely. Many Non-Resident Indians (NRIs) also worry about eligibility, documentation, taxation, and whether they can complete the purchase without traveling to India.
This guide explains the rules governing NRI buying property in India, the types of properties NRIs can purchase, the documents required, and the buying process. It is designed to help you understand the essentials before making an investment.
Yes. NRIs are permitted to buy residential and commercial immovable property in India. The purchase is governed by the Foreign Exchange Management Act (FEMA) and related rules issued by the Reserve Bank of India (RBI).
In most cases, NRIs do not require prior RBI approval to purchase eligible residential or commercial property. Payment for the property must generally be made through approved banking channels, such as inward remittance from abroad or funds held in NRE, NRO, or FCNR accounts.
Whether you're purchasing your first home, investing in an apartment, or buying office space, understanding the applicable rules before signing an agreement can help avoid legal or financial complications.
Example: An Indian citizen working in the United States can purchase an apartment in Bengaluru using funds remitted through an NRE account, provided all legal and banking requirements are met.
Not every property category is available to NRIs. Indian regulations distinguish between permitted and restricted property types.
| NRIs Can Buy | NRIs Generally Cannot Buy |
|---|---|
| Residential apartments | Agricultural land |
| Independent houses | Farmhouses |
| Residential plots (where permitted) | Plantation property |
| Commercial offices | |
| Shops and commercial units |
According to RBI regulations, NRIs and OCIs are generally allowed to purchase residential and commercial immovable property, while the direct purchase of agricultural land, plantation property, and farmhouses is restricted.
Yes. Although NRIs generally cannot purchase agricultural land directly, they may acquire agricultural property through inheritance, subject to applicable laws. The rules governing inherited property differ from those for direct purchases.
The following individuals are generally eligible to purchase residential or commercial property in India:
Non-Resident Indians (NRIs)
Overseas Citizens of India (OCIs)
Eligible Persons of Indian Origin (where applicable under current regulations)
Foreign nationals who are not of Indian origin are subject to different regulations and should review the applicable RBI and FEMA provisions before planning a purchase.
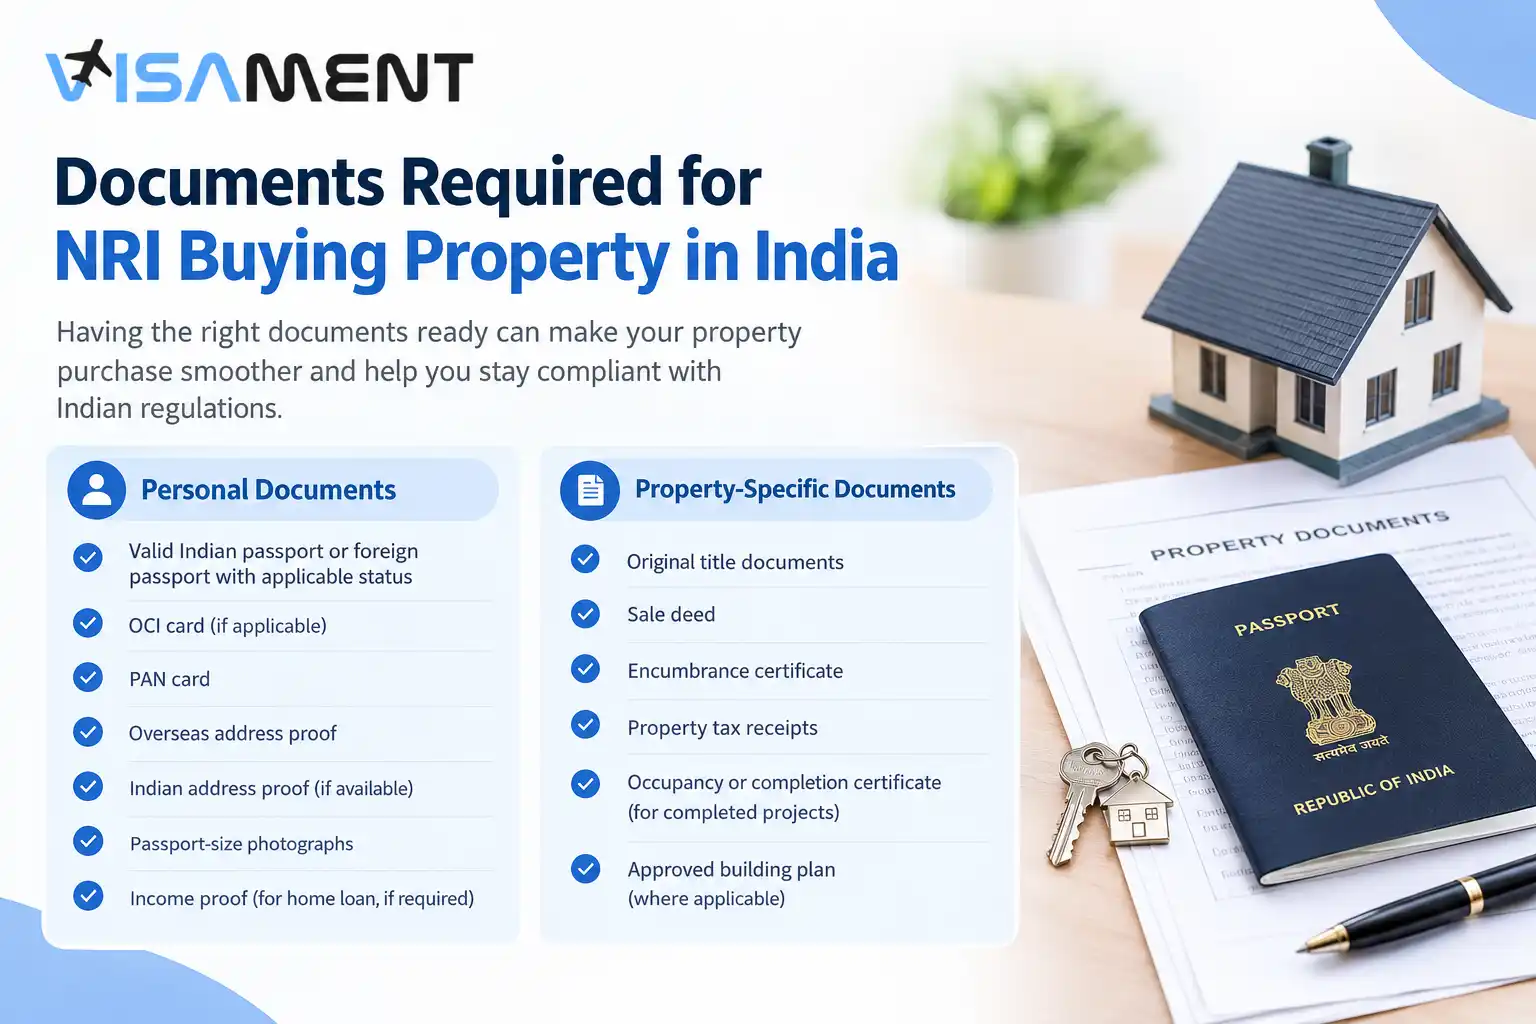
The exact documentation depends on the property type, lender (if financing is involved), and state registration requirements. However, most NRIs should expect to provide the following:
Valid Indian passport or foreign passport with applicable status
OCI card (if applicable)
PAN card
Overseas address proof
Indian address proof (if available)
Passport-size photographs
Income proof (particularly when applying for a home loan)
Bank account details (NRE/NRO/FCNR account, where applicable)
Power of Attorney documentation (if someone will represent the buyer)
Before signing any agreement, verify that the seller provides:
Original title documents
Sale deed
Encumbrance certificate
Property tax receipts
Occupancy or completion certificate (for completed projects)
Approved building plan (where applicable)
Following a structured process helps reduce legal and financial risks.
Begin by calculating your investment budget, financing requirements, currency exchange considerations, and additional costs such as stamp duty, registration charges, and legal expenses.
If you're considering financing, compare NRI home loan options offered by Indian banks before finalizing a property.
Research developers, locations, and resale properties carefully.
Consider factors such as:
Location and connectivity
Builder reputation
Legal approvals
Infrastructure development
Rental demand (if purchasing for investment)
Future resale potential
Avoid making decisions based solely on promotional material or projected returns.
Legal verification is one of the most important stages of buying property in India.
Before making any payment, ensure:
The seller has a clear and marketable title.
The property has no pending legal disputes.
Required approvals have been obtained.
There are no outstanding loans or encumbrances against the property.
Professional legal verification can help identify issues that may not be immediately visible in the property documents.
Once legal verification is complete and both parties agree on the terms, the buyer usually pays a booking or token amount before signing the Agreement to Sell.
The agreement generally specifies:
Purchase price
Payment schedule
Possession timeline
Obligations of both parties
Conditions for cancellation
Review every clause carefully before signing the agreement.
Need assistance with documentation such as a PAN card or other NRI-related paperwork before purchasing property? Consider consulting an experienced NRI documentation or taxation professional to ensure compliance with current regulations.
NRIs must make property payments through approved banking methods in accordance with applicable FEMA regulations. Payments are generally made using:
Funds remitted from abroad through normal banking channels
NRE (Non-Resident External) Account
FCNR (Foreign Currency Non-Resident) Account
Avoid making payments through unofficial channels. Keep records of all remittances and transaction receipts for future reference and taxation purposes.
After completing the payment formalities, the property must be registered with the applicable State Registration Department.
Registration typically involves:
Executing the sale deed
Paying applicable stamp duty
Paying registration charges
Recording ownership with the local registration authority
Registration requirements and charges vary by state, so verify the latest rules before completing the transaction.
 Also Want to Know About Can NRIs Extend Their Stay in India? Check Now!
Yes. NRIs can purchase property without being physically present in India by appointing a trusted representative through a legally executed Power of Attorney (PoA).
The appointed representative can perform activities such as:
Signing documents
Completing registration formalities
Coordinating with developers
Representing the buyer before government authorities
If the Power of Attorney for property is executed outside India, it generally needs to comply with the applicable authentication and registration requirements before being accepted in India. Since procedures may vary, verify the latest requirements with the relevant authorities or a legal professional.
Also Want to Know About NRI Documentation Checklist for India (2026) Check Now!Many Indian banks and housing finance companies offer home loans specifically for NRIs.
While eligibility differs by lender, financial institutions commonly evaluate:
Employment status
Country of residence
Income stability
Creditworthiness
Existing financial obligations
Property value
Typical documents requested include:
Passport
Visa or residence permit (where applicable)
PAN card
Income proof
Overseas employment documents
Bank statements
Compare loan terms, interest rates, repayment options, and processing fees before choosing a lender.
Buying property involves certain statutory charges in addition to the purchase price.
These may include:
Stamp Duty: Levied by the respective state government.
Registration Charges: Paid for registering the property in the buyer's name.
Tax Deduction at Source (TDS): Applicable in specific situations under the Income-tax Act.
The exact amount depends on factors such as property value, location, and prevailing regulations. Since tax provisions can change, always verify the latest requirements with the Income Tax Department or a qualified tax professional.
Note: This guide provides only a general overview of taxation. Detailed topics such as capital gains tax, TDS compliance, and ongoing property tax obligations should be covered in dedicated articles.
Purchasing property from overseas requires careful planning. Avoid these common mistakes:
Never rely solely on the seller's assurances. Verify ownership, title, approvals, and encumbrances before making payment.
Ensure the purchase complies with the applicable FEMA provisions, especially regarding eligible property types and payment methods.
Besides the purchase price, account for:
Stamp duty
Registration fees
Legal charges
Home loan processing fees (if applicable)
Maintenance charges
When buying under-construction property, research the developer's reputation, delivery history, approvals, and project registration before investing.
Keep copies of every agreement, receipt, remittance record, and registration document. Proper documentation simplifies future tax filings, ownership verification, and property transactions.
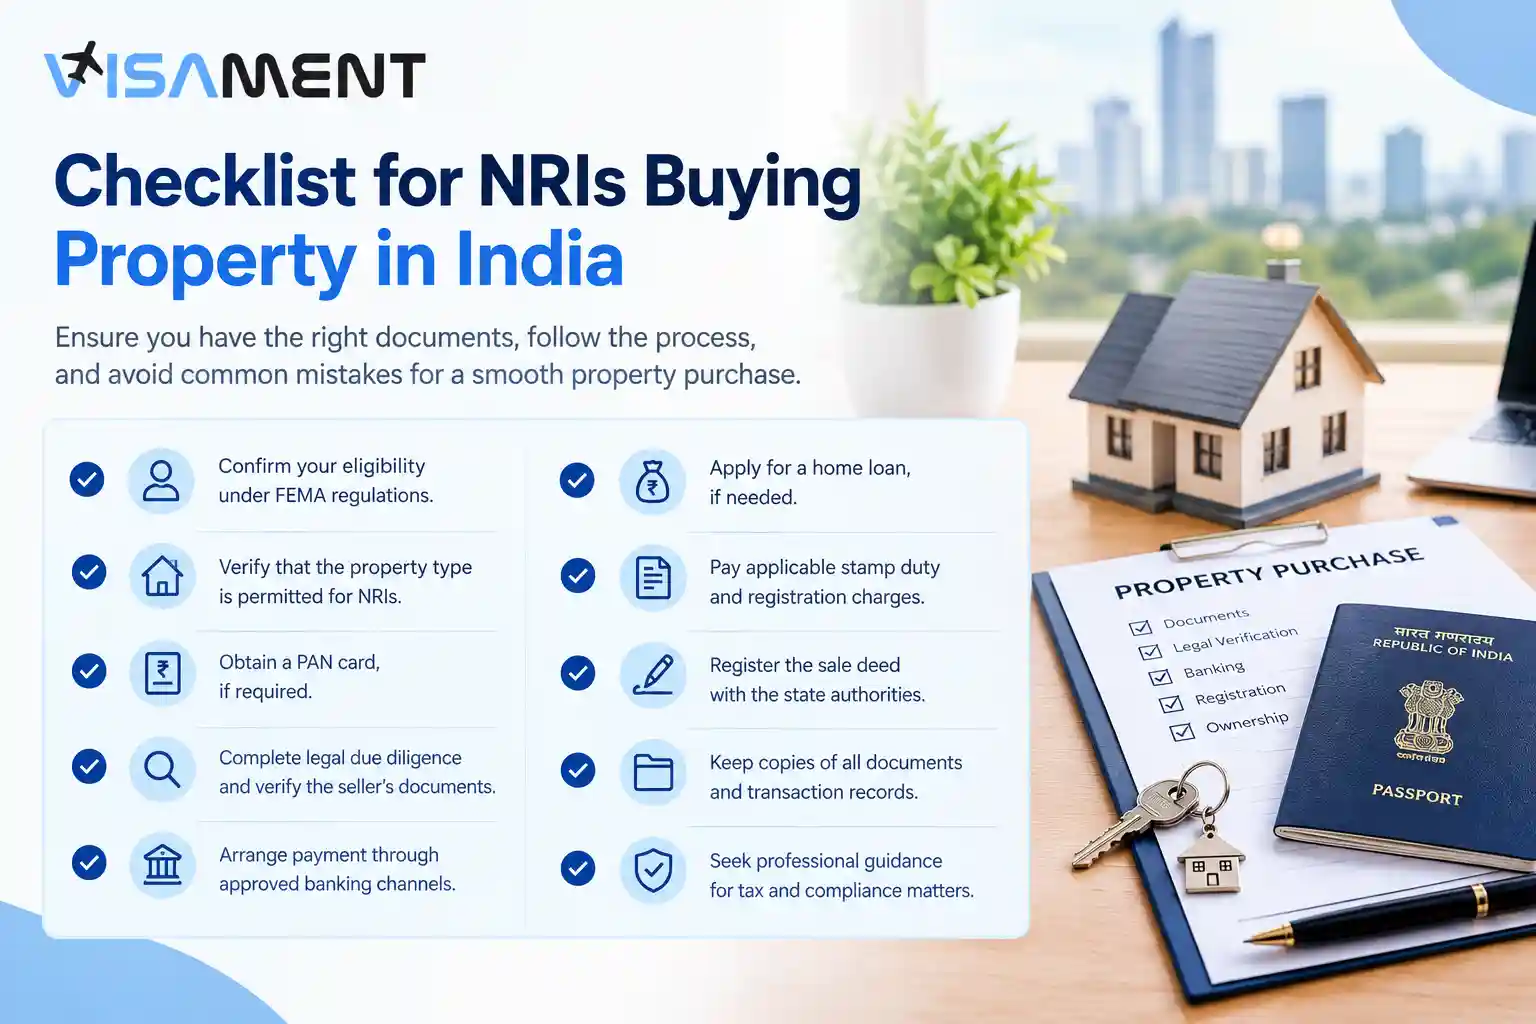
Before finalizing your purchase, ensure you have completed the following:
✔ Confirm your eligibility under FEMA regulations.
✔ Verify that the property type is permitted.
✔ Obtain a PAN card, if required.
✔ Complete legal due diligence.
✔ Verify the seller's ownership documents.
✔ Arrange payment through approved banking channels.
✔ Compare NRI home loan options, if financing is needed.
✔ Pay applicable stamp duty and registration charges.
✔ Register the sale deed.
✔ Safely store all original property documents.
Stop worrying about delays. Apply now and get Indian Counsellor Services.
Chat NowBuying property in India as an NRI is entirely possible when you understand the applicable legal and financial requirements. Knowing which properties you can purchase, preparing the right documents, conducting thorough legal due diligence, and following the correct registration process can help you complete the transaction with confidence.
Before making a significant investment, verify the latest FEMA regulations, taxation rules, and state-specific registration requirements through official sources or seek professional advice where necessary.
If you need help with PAN card services, NRI taxation, property-related documentation, or other Indian compliance requirements, consult a trusted professional before completing your property purchase. Expert guidance can help ensure your transaction complies with current regulations and reduce the risk of costly mistakes.
Yes. Two eligible NRIs may jointly purchase residential or commercial property, subject to applicable legal and regulatory requirements.
OCI cardholders are generally permitted to purchase residential and commercial property under the applicable FEMA framework. However, restrictions continue to apply to agricultural land, plantation property, and farmhouses.
Aadhaar is not universally mandatory for every property purchase. Requirements can vary depending on the transaction, financial institution, and applicable regulations. Verify the latest requirements before proceeding.
Yes. Many NRIs purchase residential or commercial property for long-term investment, rental income, or future residence. Investment decisions should be based on proper legal and financial due diligence rather than market speculation.
Yes. Although NRIs generally cannot purchase agricultural land directly, they may inherit such property in accordance with applicable laws.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.
Top NRI Investment Options Available in India: Best Plans for 2026
NRI Bank Account: Types, Benefits, Eligibility & How to Choose
Difference Between an NRE and NRO Account: Tax & Eligibility
Understanding FCNR Account: Features, Eligibility & Benefits
Non-Resident Ordinary (NRO) Bank Account: What It Is and How It Works

When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.