Related Blogs

If you are an Indian citizen living outside India, you may have come across terms such as NRI, RNOR, NRE, NRO, FCNR, and OCI. These terms are related, but they do not mean the same thing. Understanding the difference is important because your residential status can affect taxation, banking, investments, property transactions, and financial compliance in India.
This guide explains what an NRI means, how NRI-related classifications work, what NRE/NRO/FCNR accounts are, and where NRI status matters. It also separates NRI status from tax residency so you can identify which rules require further checking.
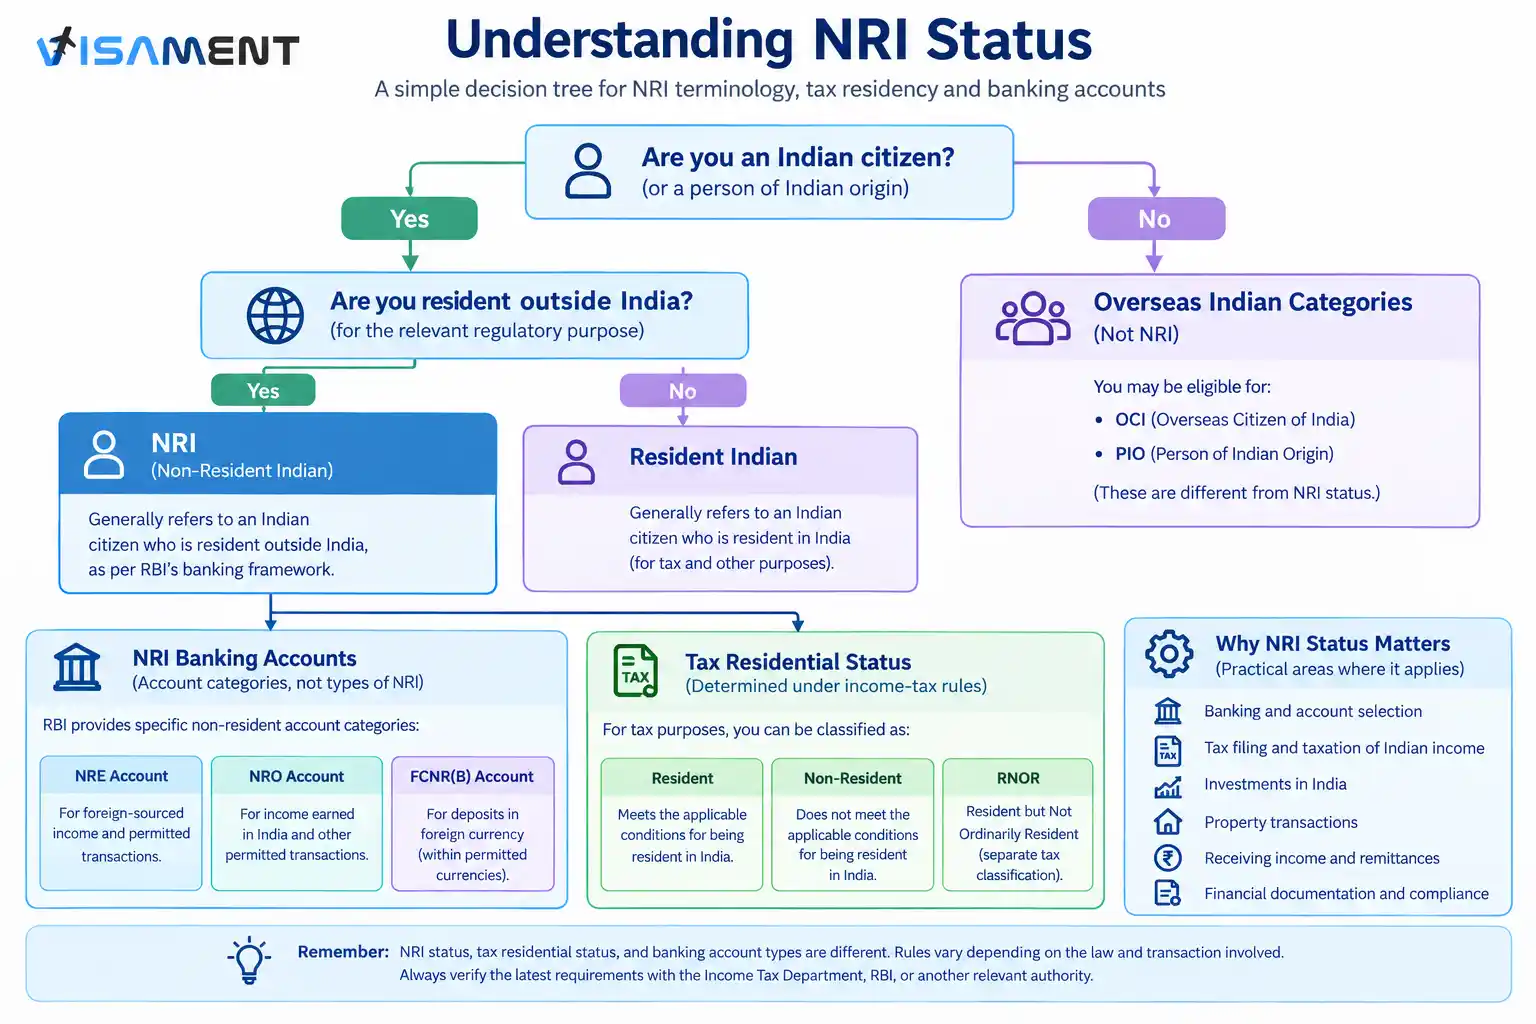
An NRI, or Non-Resident Indian, is a person resident outside India who is a citizen of India under the Reserve Bank of India's framework for non-resident accounts.
In everyday use, the term generally refers to an Indian citizen who lives outside India, such as someone working, studying, or residing abroad. However, the practical consequences of being an NRI depend on the particular regulatory framework involved.
For example, the Reserve Bank of India (RBI) uses NRI terminology in its foreign-exchange and banking framework, while the Income Tax Department determines an individual's residential status under applicable income-tax rules.
That distinction matters. Simply saying that someone is an NRI does not, by itself, answer every question about how that person's income will be taxed or which bank account they should use.
There is no single test that answers every NRI-related question. The applicable test depends on what you are trying to determine.
For Indian income-tax purposes, residential status is determined under the applicable income-tax law. For tax years governed by the Income Tax Act, 2025, the Income Tax Department states that the basic residential-status conditions remain centered on the individual's period of stay in India, with additional rules applying in specified circumstances.
For example, the current framework includes tests based on the number of days an individual is present in India during the relevant tax year and their presence during preceding years. Special provisions can apply to certain Indian citizens or persons of Indian origin who visit India or leave India in specified circumstances.
This is why an individual should not determine their tax status simply by asking, "Do I live abroad?"
Suppose an Indian citizen works in another country but spends a significant amount of time in India during a particular year. Their tax residential status may require an assessment of their days in India and other conditions under the applicable tax rules.
Therefore, an NRI-related question should always be considered in context: banking, taxation, foreign exchange, property, and other areas can have their own rules.
The phrase "types of NRI" can be misleading because several different classifications are often grouped together.
For income-tax purposes, the important residential-status categories include:
|
Classification |
What it generally means |
|---|---|
|
Resident |
The individual meets the applicable conditions for being resident in India for tax purposes. |
|
Non-Resident |
The individual does not meet the applicable conditions for being resident in India for tax purposes. |
|
RNOR |
Resident but Not Ordinarily Resident; this is a separate tax-residential classification subject to additional conditions. |
The Income Tax Department's current guidance and forms distinguish Resident, Non-Resident, and Resident but Not Ordinarily Resident for residential-status purposes.
RNOR is particularly important for people who have recently returned to India or whose residential history results in the RNOR classification under the applicable tax rules.
An RNOR classification can have different tax implications from both a resident and a non-resident. The exact treatment should therefore be assessed using the rules applicable to the relevant tax year rather than assumed from the person's location alone.
An OCI (Overseas Citizen of India) cardholder is not simply another name for an NRI. OCI relates to an immigration/citizenship-status framework for eligible foreign citizens of Indian origin, whereas NRI terminology generally concerns a person who is an Indian citizen residing outside India.
The RBI also distinguishes NRI and PIO terminology in its non-resident banking guidance.
For this reason, NRI, RNOR, OCI, and PIO should not be treated as interchangeable labels.
No. NRE, NRO, and FCNR(B) are types of non-resident Indians bank accounts, not types of people or NRI classifications.
The RBI identifies these as major account categories available within India's non-resident banking framework.
|
Account |
Full form |
Basic purpose |
|---|---|---|
|
NRE |
Non-Resident (External) Rupee Account |
A rupee-denominated account within the NRI banking framework for permitted transactions involving foreign-sourced funds. |
|
NRO |
Non-Resident Ordinary Rupee Account |
A rupee account used for permitted transactions involving income or funds connected with India. |
|
FCNR(B) |
Foreign Currency Non-Resident (Bank) Account |
A non-resident deposit account maintained in permitted foreign currencies. |
The specific eligibility, permitted transactions, taxation, interest treatment, and repatriation rules depend on the applicable regulations and account conditions. The RBI's current guidance should be checked before opening or converting an account.
This distinction is worth remembering:
NRI = person/status terminology
NRE/NRO/FCNR(B) = banking-account terminology
NRI status can become relevant in several areas of financial and administrative life in India.
NRIs may need banking arrangements designed for non-residents. RBI rules provide specific frameworks for accounts such as NRE accounts, NRO accounts, and FCNR(B) accounts.
The appropriate account depends on factors such as the nature of funds, currency, intended transactions, and applicable repatriation rules.
NRI-related tax treatment depends on residential status and the nature and source of income, rather than simply on whether a person lives abroad.
For example, an NRI may have income connected with India even while earning employment income overseas. The Indian tax treatment of different types of income can vary, so detailed tax questions should be considered separately.
NRIs can have opportunities to invest in India, but investment rules can depend on the type of investment, the investor's status, and applicable Foreign Exchange Management Act (FEMA), RBI, tax, or securities regulations.
A broad statement that "NRIs can invest in everything in India" would therefore be misleading.
NRI status can also matter when buying, selling, gifting, or inheriting property in India. Property transactions involving non-residents are subject to applicable foreign-exchange and other legal requirements.
The RBI provides specific guidance on transactions involving immovable property and NRIs/OCIs.
NRIs may receive, hold, transfer, or repatriate funds subject to the rules applicable to the particular transaction and account.
Repatriation should not be assumed to be unrestricted. The source of funds, account type, transaction, tax compliance, and applicable RBI/FEMA requirements can all matter.
An individual's residential status can also affect how financial institutions and authorities handle documentation, tax forms, accounts, and transactions.
This is one reason it is useful to establish the correct status before completing an important financial transaction.
The simplest distinction is that an NRI generally refers to an Indian citizen who is resident outside India, while a resident Indian is treated as resident under the applicable regulatory or tax framework.
However, the practical difference depends on the specific activity.
|
Area |
NRI |
Resident Indian |
|---|---|---|
|
Residential status |
Generally resident outside India in the relevant NRI framework |
Generally resident in India |
|
Banking |
Subject to non-resident banking rules where applicable |
Generally uses resident banking arrangements |
|
Taxation |
Depends on applicable residential status and income |
Depends on applicable residential status and income |
|
Foreign exchange |
Specific FEMA/RBI rules may apply |
Different FEMA treatment may apply |
|
Investments/property |
Certain transactions have specific non-resident rules |
Generally subject to resident rules |
The table is a conceptual comparison rather than a complete statement of every legal rule. The applicable law should always be checked for the transaction involved.
Before opening an account, investing, transferring funds, filing taxes, or completing a property transaction, check:
This approach is safer than assuming that every person living abroad is subject to the same NRI rules.
NRE is not a type of NRI. It is a non-resident bank-account category.
RNOR is not simply another name for NRI. RNOR is a tax-residential classification with its own conditions.
OCI is not the same as NRI. OCI status and NRI terminology belong to different legal and administrative concepts.
Living abroad does not automatically answer every tax question. Indian tax residential status must be determined under the applicable income-tax rules.
NRI status does not automatically mean every financial transaction is permitted. Banking, investment, property, remittance, and tax rules can differ depending on the transaction.
Understanding what an NRI is, the different NRI-related classifications, and their practical uses starts with separating concepts that are often incorrectly grouped together. NRI generally describes an Indian citizen residing outside India, while tax residential status is determined under applicable income-tax rules. RNOR is a tax classification, and NRE, NRO, and FCNR(B) are banking-account categories rather than types of NRIs.
NRI status can matter for NRI income tax, banking, investments, property, remittances, and financial documentation. Because these rules depend on the specific transaction and can change over time, always verify the current requirements with the Income Tax Department, RBI, or another relevant authority before making an important financial or legal decision.
To qualify as an NRI, an individual must be outside India for 182 days or more during a single financial year.
There is no absolute limit on how long an NRI can stay in India. However, the duration of your stay directly affects your residential status under the Income Tax Department.
The 90% rule for non-residents is a special tax provision under the Canadian Income Tax Act. This allows newcomers or part-year residents to claim the full amount of federal non-refundable tax credits.
There are many disadvantages of being an NRI, such as financial and lifestyle challenges, limited access to government investment schemes and currency fluctuation risks.
For NRIs, only the income that is received, accrued or arises in India is taxable.
For an NRI, the basic tax-free limit in India depends on the tax regime you have chosen. Rs. 2.5 lakh (old tax regime) and Rs. 4 lakh (new tax regime).
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.
When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.