Related Blogs

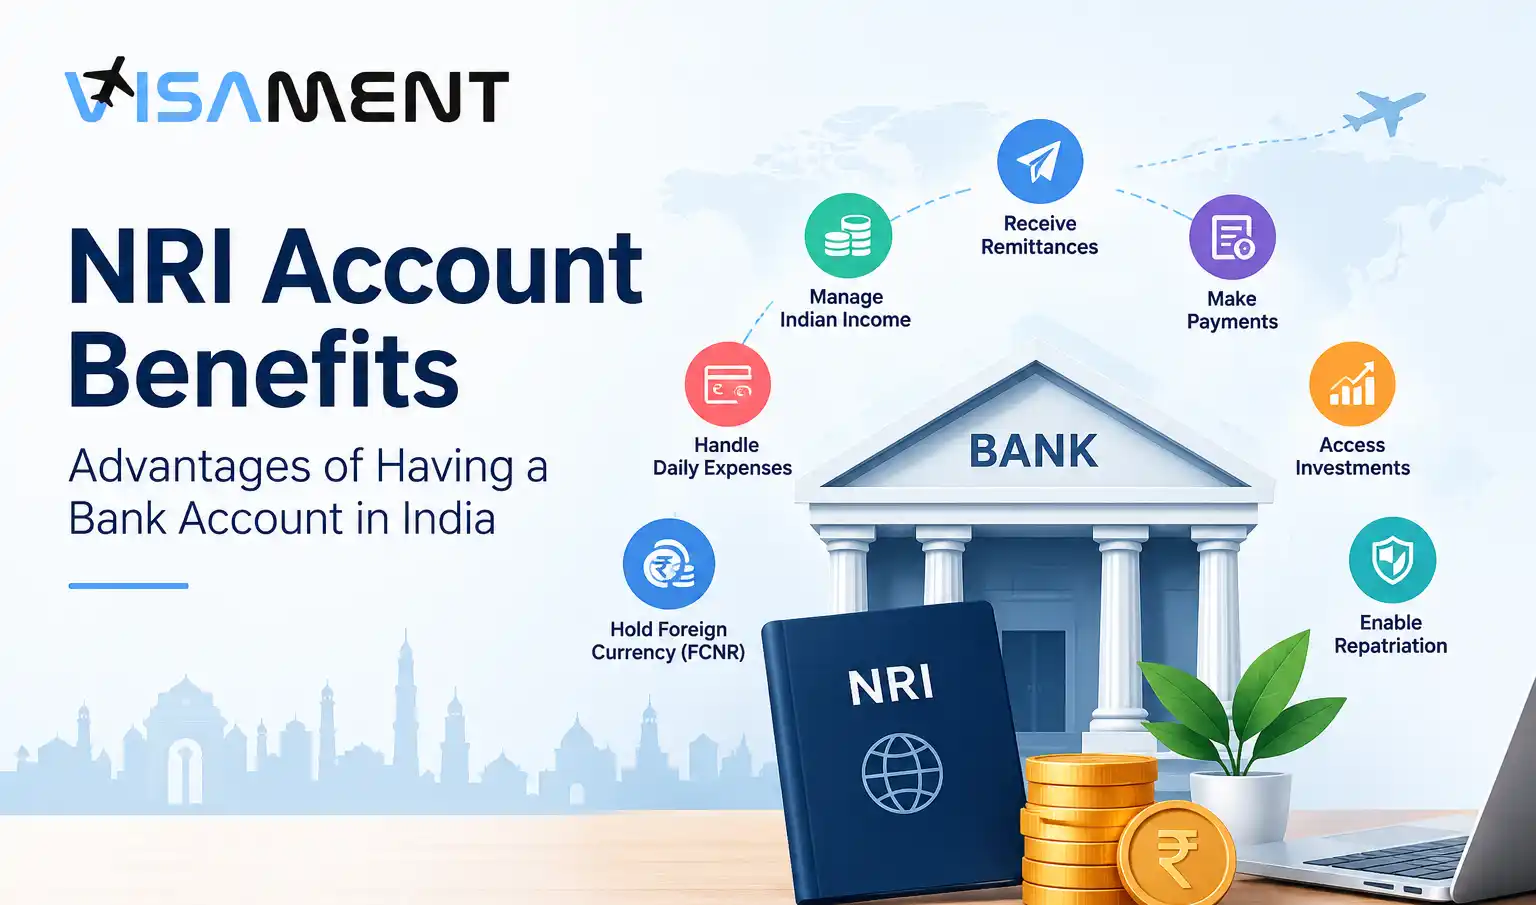
If you live outside India but still have income, family expenses, investments, property, or other financial commitments in India, managing money through the appropriate NRI bank account can make those transactions more structured. The main NRI account benefits depend on whether you use an NRE, NRO, or FCNR(B) account, because each account serves a different purpose. This guide explains the practical advantages of NRI banking, how the three account types differ, and what to consider before choosing an account.
An NRI bank account is an account permitted under India's foreign-exchange framework for eligible non-residents to manage funds in India. The principal account categories are Non-Resident External (NRE), Non-Resident Ordinary (NRO), and Foreign Currency Non-Resident (Bank) (FCNR(B)) accounts.
The accounts are not interchangeable. An NRE account is a rupee-denominated account generally used for eligible foreign-sourced funds. An NRO account is a rupee account commonly used for managing Income Tax for NRIs. An FCNR(B) account is a term deposit maintained in an eligible foreign currency. The Reserve Bank of India (RBI) sets the framework governing these accounts.
That distinction matters because the benefits available to an NRI depend largely on where the money comes from, what the account is being used for, and whether the funds need to be transferred outside India.
One of the biggest advantages of an NRI bank account is convenience. An NRI may continue to have financial commitments in India even after moving abroad, including household expenses, property-related costs, investments, insurance payments, or loan obligations.
Using the appropriate NRI account provides a designated banking arrangement for eligible transactions rather than trying to manage Indian financial activities through an account intended for residents.
For someone who has moved abroad permanently or for an extended period, keeping the account structure aligned with their residential status is also important for regulatory compliance.
Many NRIs continue to receive income from India. Examples can include rent, pension, dividends, interest, or other eligible Indian-source income.
An NRO account is generally used for managing income earned in India. The RBI's guidance specifically describes NRO accounts as being available for local receipts and Indian transactions.
The tax treatment of that income depends on the nature of the income, the account involved, the individual's circumstances, and applicable tax rules. An NRI account should therefore not be viewed as a way to automatically eliminate Indian tax obligations.
NRIs may need to transfer part of their overseas earnings to India for family expenses, investments, savings, or other legitimate purposes.
An appropriate NRI account can provide a structured destination for eligible inward remittances. For example, the RBI framework permits eligible foreign-sourced funds to be credited to NRE accounts through permitted channels.
The account type matters because foreign remittances and Indian-source income are not treated identically under the NRI banking framework.
Another practical benefit is the ability to manage eligible Indian payments from the account.
Depending on the account and applicable rules, an NRI may use the account for expenses such as:
This can reduce the need to depend on informal transfers or maintain inappropriate resident-account arrangements.
NRI banking can also support eligible deposits and investments in India, subject to the rules applicable to the individual, investment and account type.
For example, NRIs may use permitted NRI accounts for certain deposits, while the RBI also provides rules governing investments by NRIs through specified routes. The precise eligibility and repatriation treatment can vary, so investment decisions should be checked against current regulations rather than assumed from the account type alone.
Repatriation is an important consideration for an NRI who may eventually want to move funds from India back overseas.
However, NRI repatriation is not an identical benefit across all NRI accounts. The RBI states that NRE balances are repatriable, while NRO balances are subject to specific conditions and limits. Current RBI guidance states that eligible NRO balances can generally be remitted up to USD 1 million per financial year, subject to the applicable conditions.
Therefore, an NRI should consider future repatriation requirements before choosing an account rather than assuming that all balances can be transferred abroad in the same way.
An FCNR(B) account can be useful for an NRI who wants an eligible term deposit maintained in a permitted foreign currency rather than converting the deposit into Indian rupees.
This can be relevant when currency exposure is an important consideration. However, FCNR(B) accounts have their own eligibility, maturity, currency, interest, and regulatory conditions. They should be evaluated separately from ordinary NRE and NRO rupee accounts.
The following is a high-level comparison. It is not a substitute for checking the current rules applicable to your circumstances.
|
Account |
Main purpose |
Currency |
Typical use |
Repatriation |
Tax consideration |
|---|---|---|---|---|---|
|
NRE |
Managing eligible foreign-sourced funds in India |
Indian rupees |
Overseas earnings and savings |
Generally repatriable, subject to applicable rules |
Interest can qualify for exemption when the statutory conditions are met |
|
NRO |
Managing income arising in India |
Indian rupees |
Rent, pension and other Indian-source income |
Subject to applicable conditions and limits |
Interest is generally taxable in India |
|
FCNR(B) |
Holding eligible deposits in foreign currency |
Permitted foreign currency |
Foreign-currency term deposits |
Generally repatriable, subject to applicable rules |
Tax treatment depends on applicable conditions |
The RBI identifies NRE and FCNR(B) deposits as repatriable, while NRO balances have different repatriation conditions.
Tax treatment also needs careful attention. The Income Tax Department's current guidance confirms that the exemption for qualifying NRE-account interest has been retained under the Income Tax Act, 2025, subject to the relevant conditions.
That does not mean all NRI account interest is tax-free. Account type and the individual's circumstances matter.
The right account depends on what you are trying to accomplish.
These examples are general guidance, not individualized financial advice. The appropriate choice depends on your residential status, source of funds, financial objectives, tax position, and applicable regulations.
 Also Want to Know About NRI Account Opening in Dubai? Check Now!
The benefits of an NRI account should be considered alongside its rules and limitations.
Before opening or redesignating an account, check:
Do not assume that an account's tax treatment or repatriation rules remain unchanged indefinitely. RBI regulations and Indian tax provisions can change, so current official guidance should be checked before making a financial decision.
A simple way to narrow your options is to start with the source and intended use of your money.
Ask yourself:
The goal is not to find a universally “best” NRI account. It is to choose an account structure that fits your circumstances and complies with the applicable RBI, FEMA, banking, and tax requirements.
Stop worrying about delays. Apply now and get Indian Counsellor Services.
Chat NowAn NRI bank account can make it easier to manage Indian financial responsibilities while living abroad, but the benefits depend on choosing the appropriate account type. NRE, NRO, and FCNR(B) accounts are designed for different purposes, particularly when it comes to the source of funds, currency, taxation, and repatriation.
Before opening or changing an account, consider how you receive money, what Indian expenses or income you manage, whether you need foreign-currency deposits, and whether you expect to move funds outside India. Because banking and tax rules can change, verify the current requirements with the RBI, your bank, and the applicable tax authorities before making a decision.
An NRI account can help eligible non-residents manage Indian income and expenses, receive permitted remittances, maintain eligible deposits, make local payments, and manage funds under the applicable NRI banking framework.
Yes, an NRI can receive eligible Indian-source income through the appropriate account. NRO accounts are generally used for income arising in India, subject to applicable banking and tax rules.
NRE accounts are generally designed for eligible foreign-sourced funds held in Indian rupees, while NRO accounts are generally used to manage income arising in India. Their tax and repatriation treatment also differs.
The answer depends on the account type and source of funds. NRE and FCNR(B) balances generally have repatriable characteristics, while NRO balances are subject to specific regulatory conditions and limits.
Tax treatment depends on the type of account and the applicable tax provisions. For example, the Income Tax Department confirms that qualifying NRE-account interest continues to receive the applicable exemption subject to statutory conditions.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.

When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.