If you return to India after living abroad, you may become a Resident but Not Ordinarily Resident (RNOR) for Indian income-tax purposes. RNOR taxation is different from both Non-Resident and Resident and Ordinarily Resident (ROR) taxation, particularly when you have income or assets outside India.
For an RNOR, Indian-source income generally remains taxable in India, while certain foreign-source income may fall outside the Indian tax scope. However, foreign income is not automatically tax-free: the source of the income, where it is received, and whether it arises from a business controlled from India or a profession set up in India can affect the result.
This guide explains the taxability of common Indian and foreign income for RNOR citizens, along with foreign-asset reporting, ITR selection, foreign tax credit and the transition from RNOR to ROR.
Key Takeaways
- RNOR is a tax-residential category, not another name for NRI.
- Indian-source income and income received or deemed received in India can be taxable for an RNOR.
- Foreign-source income generally has a narrower Indian tax exposure for an RNOR than for an ROR.
- Foreign-source income from a business controlled from India or a profession set up in India can fall within Indian taxation.
- Foreign-income taxability and foreign-asset disclosure are separate questions.
- RNORs cannot use ITR-1 or ITR-4 under the current return eligibility rules.
- Residential status is determined separately for each tax year, so the applicable law and facts for that particular year must be checked.
A Practical RNOR Tax Checklist
Before filing your Indian income-tax return, check:
- Your residential status for the specific tax year.
- The law applicable to that tax year.
- Indian salary, rent, interest, dividends and capital gains.
- Foreign salary, pension, interest, dividends and capital gains.
- Any foreign business or professional activity controlled or established from India.
- Foreign tax already paid.
- Applicable DTAA or foreign-tax-credit provisions.
- Foreign accounts and assets and whether any reporting schedule applies.
- Whether ITR-2, ITR-3, or another return is appropriate.
- Whether your circumstances indicate that you may become ROR in a subsequent year.
If you need help organizing Indian tax and NRI documentation, professional documentation support can help you prepare the relevant records before discussing the tax treatment with your Chartered Accountant or tax adviser.
What Is RNOR Status in India?
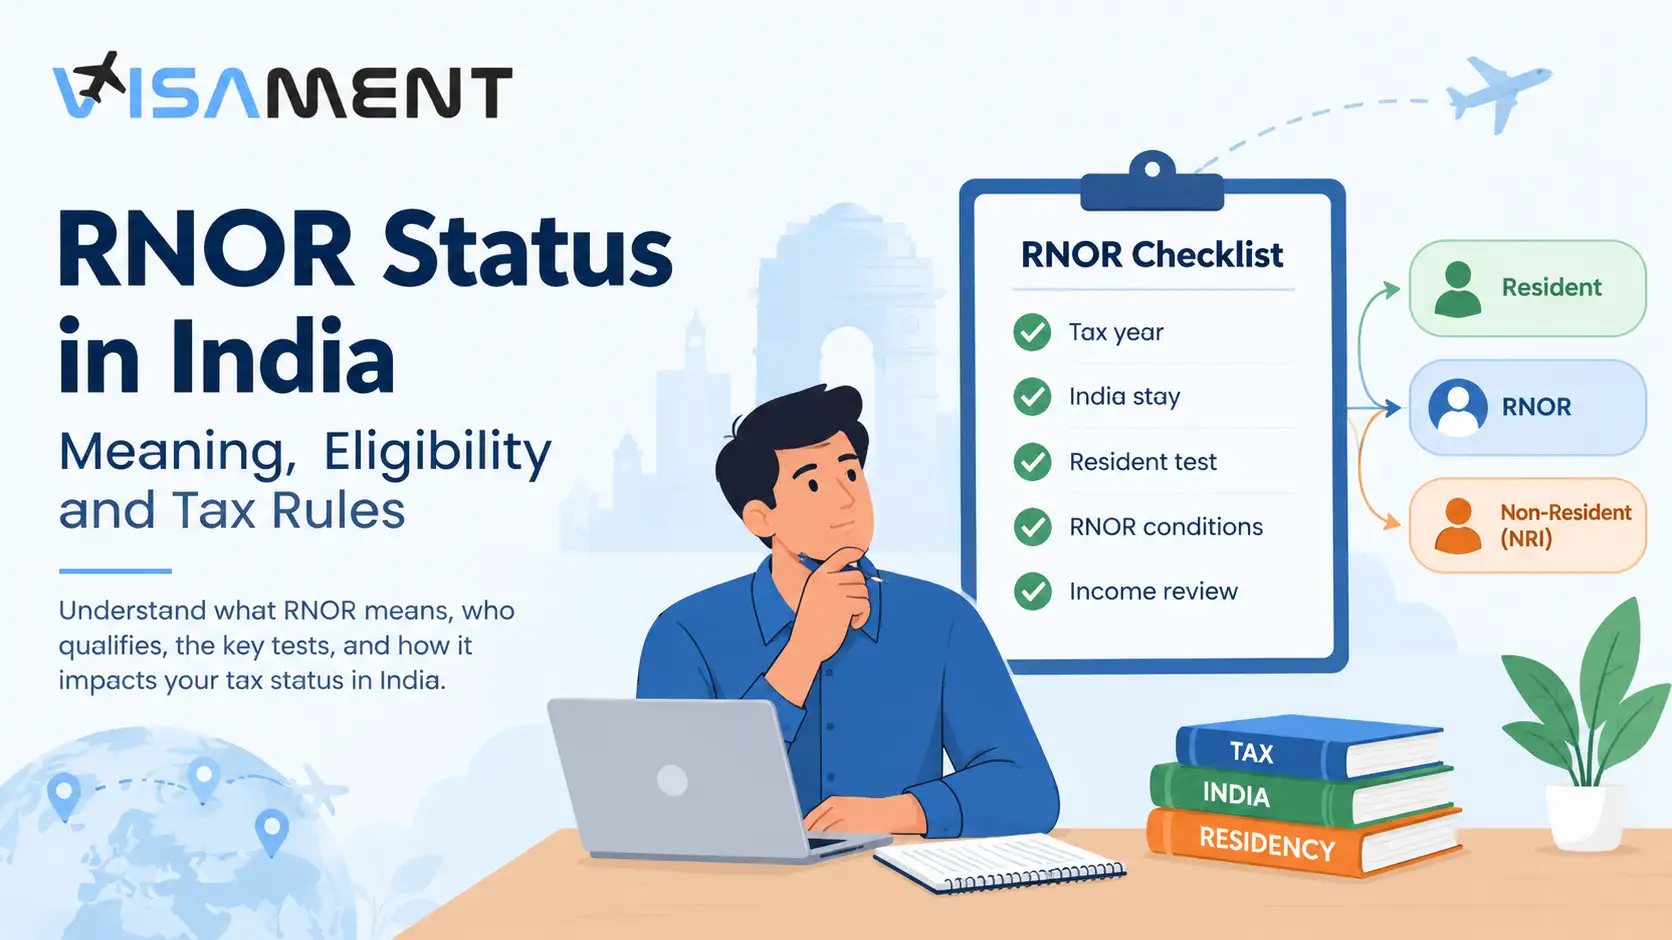
RNOR stands for Resident but Not Ordinarily Resident. It is a category of Indian tax residency that generally applies to individuals who satisfy the conditions for being resident in India but have not met the conditions for being treated as ordinarily resident.
For many returning Indians, the commonly used RNOR tests involve whether the individual was a non-resident in 9 out of the 10 preceding years or was present in India for 729 days or less during the 7 preceding years. The Income Tax Act, 2025 retains these continuity-based tests.
There are also statutory rules dealing with certain deemed-resident and returning-citizen situations, so RNOR status should not be determined solely from a general three-year rule.
For tax years beginning before April 1, 2026, residential status is determined under the Income-tax Act, 1961. For tax years beginning on or after April 1, 2026, the Income Tax Act, 2025 applies.
The important point is that RNOR status must be determined separately for each tax year.
[Insert image: Comparison of Non-Resident, RNOR and ROR taxability in India | Alt text: "Comparison of Non-Resident, RNOR and ROR income tax treatment in India"]
How Is Income Taxed for an RNOR?
The simplest way to understand RNOR taxation is to classify income according to its Indian or foreign connection.
For an RNOR, the Indian tax scope generally includes:
-
Income received or deemed to be received in India.
-
Income that accrues or arises, or is deemed to accrue or arise, in India, whether or not it is actually received in India.
-
Certain foreign-source income derived from a business controlled in India or a profession set up in India.
Other foreign-source income that accrues and is received outside India will generally have a different treatment for an RNOR than it would for an ROR.
This is why the statement “RNORs do not pay tax on foreign income” is too broad. The correct tax treatment depends on the nature, source and circumstances of the income.
| Income situation |
General RNOR treatment |
| Indian salary |
Generally taxable in India |
| Rent from Indian property |
Generally taxable in India |
| Indian bank interest |
Generally taxable, subject to applicable provisions |
| Indian dividends |
Generally taxable, subject to applicable provisions |
| Taxable Indian capital gains |
Generally taxable |
| Foreign-source investment income received outside India |
Generally outside the RNOR Indian tax scope, subject to applicable rules |
| Foreign-source income from a business controlled in India |
Can be taxable in India |
| Foreign income received in India |
Receipt/source rules must be examined |
Which Indian Income Is Taxable for an RNOR?
RNOR status does not provide a general exemption from Indian income tax.
Income connected with India can remain taxable, subject to the relevant exemptions, deductions and provisions. Common examples include:
- Salary for services that are taxable in India
- Rental income from Indian property
- Interest from Indian bank deposits
- Dividends from Indian investments
- Income from an Indian business or profession
- Taxable gains from the transfer of Indian assets
- Other income that accrues or arises in India
For example, if a returning Indian citizen qualifies as an RNOR and receives rent from an apartment located in India, the fact that the individual also has overseas income does not make the Indian rental income foreign income.
The applicable tax rate and deductions depend on the income type and the tax regime for the relevant year.
Is Foreign Income Taxable for an RNOR?
Foreign-source income is generally treated more narrowly for an RNOR than for an ROR. However, an RNOR should not assume that every amount earned outside India is automatically exempt from Indian tax.
The analysis can change where the income is received in India or where the foreign-source income falls within a statutory exception, particularly income derived from a business controlled in India or a profession set up in India.
The distinction becomes important when an RNOR continues to have overseas employment, investments, retirement accounts or business interests after returning to India.
Foreign Salary or Employment Income
Foreign salary requires a fact-specific analysis. The place where services are performed, the nature of the employment, where the income accrues, and where payment is received can all matter.
For example, simply describing a payment as “foreign salary” does not by itself establish that the income is outside Indian taxation. An RNOR who has returned to India but continues working for an overseas employer should review the actual work arrangement and source of the employment income.
Foreign Interest and Dividends
Interest from an overseas bank account and dividends from foreign securities are generally foreign-source investment income. For an RNOR, such income may fall outside the Indian tax scope when the statutory conditions for foreign-source income are satisfied.
However, the analysis should not stop at the location of the bank or investment. Receipt in India, the nature of the income, and the applicable tax rules should also be considered.
Foreign Pension
Foreign pensions can be particularly complicated because the tax treatment may depend on the source of the pension, the underlying retirement arrangement, where the pension is received and whether a tax treaty applies.
An RNOR should therefore avoid assuming that every overseas pension withdrawal is automatically exempt in India.
Foreign Capital Gains
Capital gains from foreign shares, securities or property require separate analysis.
The fact that the underlying asset is located outside India does not, by itself, answer every tax question. The type of asset, transfer, source of income, place of receipt and applicable Indian provisions should be examined.
If the same gain is also taxable in another country, DTAA and foreign-tax-credit rules may become relevant.
Foreign Business or Professional Income
This is one of the most important exceptions for RNOR taxpayers.
Foreign-source income derived from a business controlled in India or a profession set up in India can be taxable in India even though the income arises outside India and may be received outside India.
For example, an RNOR operating an overseas-facing business from India should not assume that the foreign location of customers or bank accounts automatically keeps the business income outside Indian taxation.
The facts concerning control, management, professional setup and source should be reviewed carefully.
[Insert image: RNOR foreign-income taxability decision tree showing Indian-source income, foreign-source income and the business-control exception | Alt text: "RNOR foreign income taxability decision tree in India"]
Does an RNOR Have to Report Foreign Assets?
Taxability and disclosure are separate questions. An income item can have a particular tax treatment without that answer automatically determining every reporting obligation.
There is an important current distinction here. The Income Tax Department's Schedule FA guidance states that Schedule FA does not need to be completed where the taxpayer is classified as “not ordinarily resident” or “non-resident.” Therefore, an RNOR should not be treated in the same way as an ROR merely because the person is resident for tax purposes.
At the same time, other foreign-income reporting requirements can apply depending on the return, income and circumstances. Schedule FSI and Schedule TR, where applicable, are relevant to reporting foreign income and foreign tax relief.
Do not assume that “RNOR” means that every foreign reporting requirement disappears.
Which ITR Should an RNOR File?
An RNOR cannot use ITR-1 (Sahaj) or ITR-4 (Sugam) under the current Income Tax Department eligibility rules.
The appropriate return depends on the taxpayer's income profile. For example, ITR-2 is generally relevant for individuals who do not have income from business or profession and are not eligible for ITR-1, while ITR-3 applies where business or professional income is involved, subject to the applicable conditions.
The correct ITR should be selected based on the return rules for the relevant assessment year rather than simply choosing the form commonly used by resident individuals.
What About DTAA and Foreign Tax Credit?
An RNOR may have situations where the same income is taxable in India and another country. In those circumstances, a Double Taxation Avoidance Agreement (DTAA) or India's foreign-tax-credit provisions may provide relief, subject to the applicable conditions.
It is important to separate two questions:
First: Is the income taxable in India?
Second: If it is taxable in India and tax was also paid abroad, is foreign-tax credit or treaty relief available?
A foreign tax payment does not automatically make Indian tax disappear. The relevant treaty, domestic tax rules, and procedural requirements should be reviewed separately.
Common RNOR Tax Mistakes to Avoid
Avoid these common assumptions:
- RNOR means no Indian tax. Indian-source income can remain taxable.
- All foreign income is exempt. The business-control and profession exceptions matter.
- RNOR is the same as NRI. RNOR is a resident tax category.
- Foreign assets never need consideration. Taxability and reporting must be examined separately.
- I can file ITR-1 because I only have salary and interest. RNOR status itself makes ITR-1 unavailable.
- Foreign tax paid means no Indian tax is due. Foreign-tax credit is a separate relief mechanism.
- My status remains RNOR for three years automatically. Residential status must be determined for each tax year under the applicable law.
When Does RNOR Become ROR?
RNOR status is not a permanent classification. Residential status is determined separately for each tax year, and the applicable conditions can change as your period of residence in India increases.
When an individual becomes Resident and Ordinarily Resident (ROR), the Indian tax treatment of foreign-source income can become significantly broader. This makes the transition important for returning Indians who continue to hold foreign investments, pensions, bank accounts or other overseas income sources.
Before the start of each tax year, review your days of stay, residential history, income sources and overseas financial interests rather than relying on the status assigned in an earlier year.
Conclusion
The taxability of income for RNOR citizens in India depends on more than whether the income is described as “Indian” or “foreign.” Indian-source income generally remains within the Indian tax scope, while qualifying foreign-source income can receive narrower treatment for RNOR than for ROR. However, foreign income connected with a business controlled in India or a profession set up in India can be taxable.
The safest approach is to determine residential status separately for each tax year, classify every significant income source, consider foreign-asset reporting separately from taxability, and review DTAA or foreign-tax-credit provisions where relevant. For complex cross-border income, a qualified Indian tax professional should review the facts and the law applicable to the relevant tax year.