Related Blogs

If you live outside India and earn interest from a Non-Resident Ordinary (NRO) account, you may notice tax deducted by your bank before the interest is credited. However, Tax Deducted at Source (TDS) is not necessarily the final tax you owe. Understanding how NRO interest is taxed, when an Indian income tax return may be required, and how to check possible refunds or treaty relief can help you manage your Indian tax obligations.
An NRO account allows a person residing outside India to manage eligible rupee transactions and income in India. It may hold funds such as legitimate income earned in India, inward remittances and other permitted credits under Reserve Bank of India (RBI) rules. NRO accounts can be maintained as savings, current, recurring or fixed deposit accounts.
The main tax implication is that interest earned on an NRO account is generally taxable in India. The bank may deduct TDS, but the amount deducted and your final tax liability can differ.
Your position depends on the relevant tax year, the applicable tax legislation, your taxable income, any applicable surcharge and cess, and whether you qualify for treaty relief. Also, Foreign Exchange Management Act (FEMA) or banking classification and income-tax residential status are separate legal questions; one should not automatically be used to determine the other.
Interest credited to an NRO savings account is generally taxable under the Indian tax rules applicable to the relevant period. Even if the interest amount is relatively small, you should include it when reviewing your Indian income and tax records.
Check your bank statement or interest certificate to confirm the interest credited during the tax year. Do not assume that an amount is tax-free simply because the bank has not deducted TDS from it.
Interest earned on an NRO fixed deposit is also generally taxable in India. Depending on the deposit terms, interest may be credited periodically or at maturity. The timing of credit, the bank's reporting and withholding treatment, and the applicable tax year should be checked against the relevant rules.
|
Point |
NRO Savings Account |
NRO Fixed Deposit |
|---|---|---|
|
Interest taxation |
Generally taxable in India |
Generally taxable in India |
|
Interest records |
Savings statement or interest certificate |
Deposit statement or interest certificate |
|
TDS |
Check the applicable withholding rules and bank records |
Check the applicable withholding rules and bank records |
Your final tax liability is not determined by the account type alone. Relevant factors may include:
For general information on wider NRI tax rates and tax slabs, see Visament's NRI income tax rates and tax slabs guide. This NRO article focuses on interest earned from the account rather than all categories of NRI income.
Important tax-law update: India's Income-tax Act, 2025 applies to tax years beginning on or after 1 April 2026. Earlier periods must be assessed under the legislation applicable to those periods. Always verify the law and relevant provisions for the specific year being reviewed.
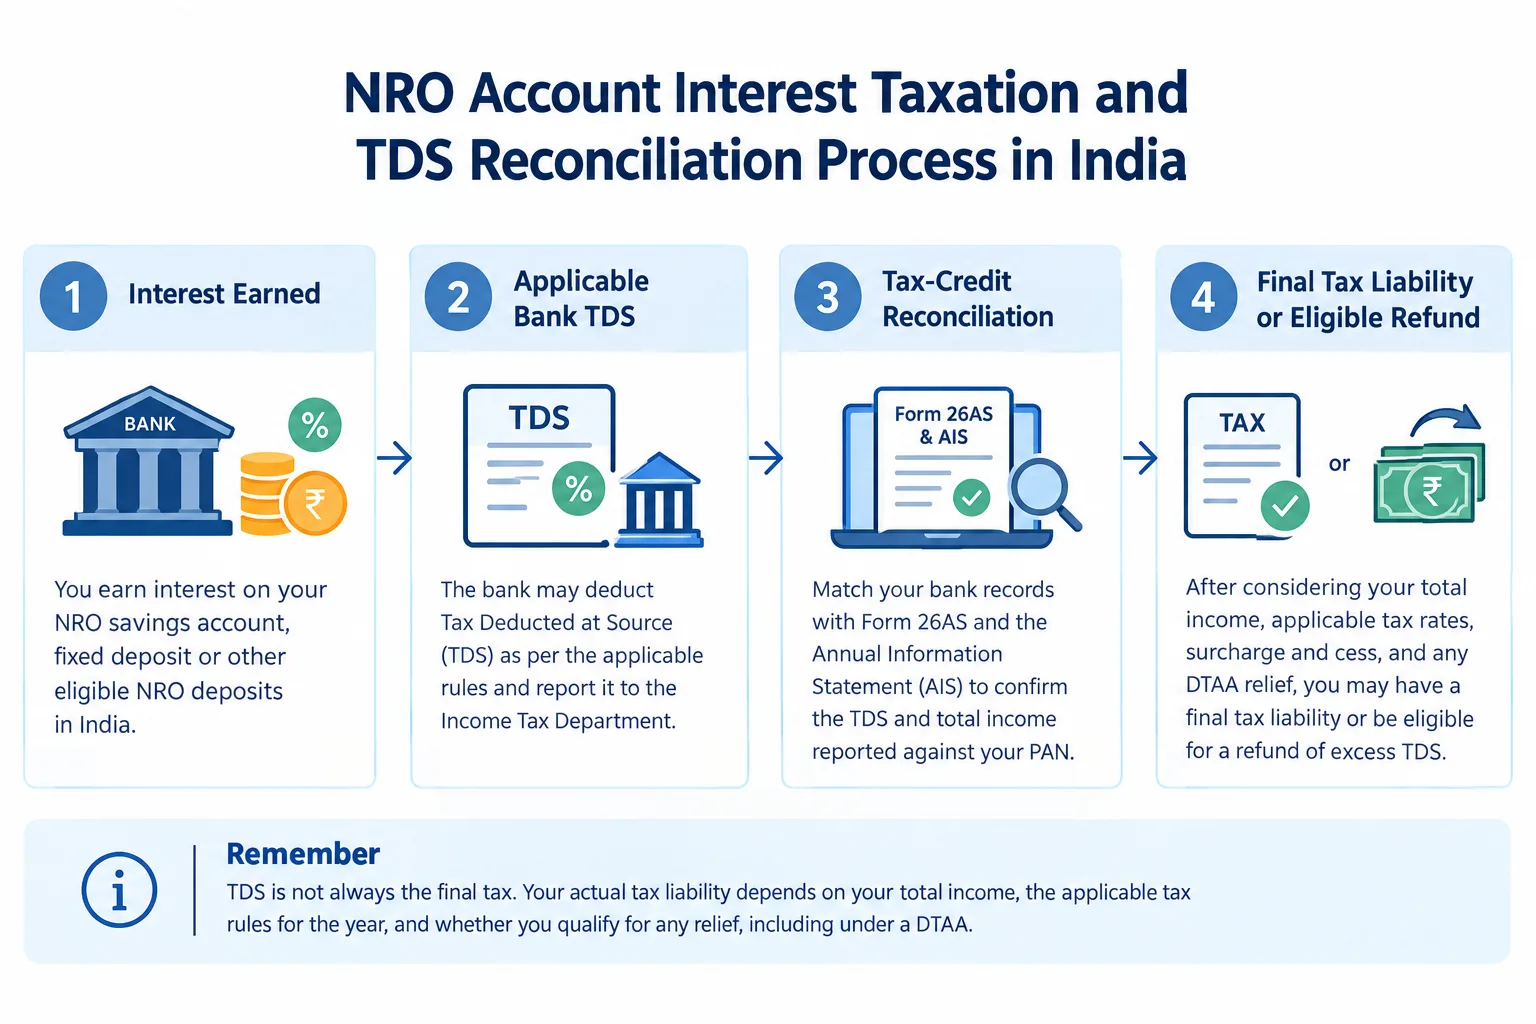
TDS is tax that a bank deducts at source when the applicable tax rules require it to do so. The bank reports the deduction against the account holder's tax details, allowing the amount to be checked against the taxpayer's official tax-credit records.
No. TDS deducted on NRO interest is not necessarily the final tax liability. The final amount depends on the law applicable to the tax year, the taxpayer's circumstances, and any eligible relief. TDS is credited against the tax liability under the applicable rules.
Avoid assuming that a particular percentage applies to every NRO account holder. Withholding rates and treaty-related treatment can depend on the payment, applicable provisions and eligibility. Check the relevant official guidance for the period involved.
Compare the bank's interest and TDS records with the tax information available through the Income Tax Department. If the tax deducted exceeds your final liability, you may be eligible to claim a refund through the applicable return process, subject to statutory requirements.
Illustrative example only: Suppose an NRO fixed deposit earns ₹1,00,000 in interest and the bank deducts ₹30,000 as TDS. If the taxpayer's correctly calculated final tax liability on that income is ₹20,000, the ₹10,000 difference may be refundable, provided the taxpayer meets the applicable requirements. These figures illustrate the arithmetic only; they do not establish a general TDS rate or tax outcome.
Whether an NRI must file an Indian income tax return depends on the applicable law, total taxable income and other statutory conditions. The fact that a bank has deducted TDS does not, by itself, determine whether filing is mandatory.
Consider these points when assessing your position:
The Income Tax Department publishes guidance for non-resident taxpayers and applicable return requirements. Check the official non-resident FAQs and the relevant filing guidance before deciding what applies to you.
For broader information about NRI taxation and return-filing considerations, read our complete guide to NRI income tax. This article is intended to explain NRO interest, not replace a complete return-filing guide.
A Double Taxation Avoidance Agreement (DTAA) may provide relief when income is taxable or subject to tax in more than one country. Whether relief applies to NRO interest depends on the relevant treaty, the taxpayer's tax residency, the nature of the income and the applicable Indian rules.
Living abroad or holding an NRO account does not automatically establish eligibility for a reduced rate or refund.
Depending on the treaty and the applicable procedure, supporting documents may include:
Requirements may vary according to the relevant tax period and current rules. Check the applicable treaty and official instructions before applying a particular rate or claiming relief. A treaty benefit may affect withholding or the final tax treatment, but neither a reduced deduction nor a refund is guaranteed.
Have questions? Our experts guide you through every step of the NRO Account Opening – no confusion, no delays.
Consult an Expert TodayNRO and Non-Resident External (NRE) accounts serve different purposes and have different tax treatments. The following comparison focuses on interest taxation rather than the full rules for opening or operating either account.
|
Comparison |
NRO Account |
NRE Account |
|---|---|---|
|
Typical purpose |
Managing eligible income and transactions in India |
Holding eligible funds remitted from abroad and other permitted credits |
|
Interest taxation in India |
Generally taxable |
Generally exempt when statutory conditions are met |
|
TDS treatment |
May apply to taxable interest under relevant rules |
Different treatment applies where the interest exemption conditions are satisfied |
|
What to verify |
Applicable tax rules, withholding and tax credits |
Eligibility, applicable exemption conditions and RBI requirements |
The RBI's guidance on accounts held by non-residents explains the permitted features of NRO and NRE accounts. The interest exemption for NRE accounts is subject to the applicable legal conditions; it should not be assumed solely from an account label.
Reviewing your bank and tax records can help you identify missing deductions, incorrect amounts or discrepancies before filing a return or seeking a refund.
The Income Tax Department explains the purpose and contents of Form 26AS and AIS. These records are useful for reconciliation, but you should not assume that every entry is automatically correct or complete.
When reviewing NRO account tax implications in India, avoid these common errors:
 Also Want to Know About Belated ITR Filling Penalty of Income Tax Return? Check Now!
NRO account interest is generally taxable in India, but TDS, final tax liability, return-filing obligations and possible relief are separate matters. Review the rules for the relevant tax year, reconcile your bank records with official tax-credit information, and seek qualified tax advice when your circumstances are unclear. For tax years beginning on or after 1 April 2026, check the applicable provisions of the Income-tax Act, 2025.
Disclaimer: This article is for general informational purposes only and is not individualized tax advice. Tax rules and filing requirements can change; verify the applicable official guidance or consult a qualified Indian tax professional before making a tax decision.
Yes. NRO fixed deposit interest is generally taxable in India, subject to the rules applicable to the relevant tax year and the taxpayer's circumstances.
No. TDS and return-filing obligations are separate questions. Whether filing is required depends on the applicable statutory conditions. A return may also be needed to claim an eligible refund.
An NRI may be eligible for a refund when tax deducted exceeds the final liability, subject to the applicable filing and refund rules. Reconcile bank records with Form 26AS and AIS before making a claim.
No. NRO interest is generally taxable in India, while qualifying NRE account interest may be exempt when the statutory conditions are satisfied.
Potentially. Relief depends on the applicable treaty, tax residency, eligibility and required documentation. Verify the current rules before claiming a benefit.
Yes, you can repatriate funds from your NRO account, but only up to a certain amount, that is, 1 million USD, in a financial year.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.
When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.