Related Blogs

Returning to India after living in the United States can affect your tax residency, overseas income, investments and filing obligations in both countries. Understanding the tax rules before relocating can help you avoid compliance mistakes and plan your finances more effectively. This guide explains Indian residential status, RNOR, continuing US tax obligations, double-taxation relief and the practical steps NRIs should consider before moving back.
The tax implications for NRIs returning to India depend on their Indian residential status, US tax status, income sources and the nature of their assets. You may need to review your Indian income-tax obligations while continuing to file US tax returns.
The main areas to consider are:
The correct treatment depends on your circumstances and the tax year concerned. A tax rule that applies to one returning NRI may not apply to another.
Your Indian tax residency is determined under the applicable Indian income-tax legislation for the relevant tax year. It is not decided simply by whether you consider India your permanent home.
The applicable residence tests generally consider the number of days you spend in India, alongside other statutory conditions and exceptions. Certain rules can differ depending on your citizenship, Indian-origin status, income and previous residency.
For this reason, track your arrival and departure dates and review your circumstances for each relevant tax year. Do not assume that spending less than six months in India automatically makes you a non-resident.
RNOR and ROR are two residential classifications that can significantly affect how foreign income is treated in India.
|
Status |
General tax implications |
|---|---|
|
Non-resident |
Generally taxed in India on income received, accruing or deemed to be received or accruing in India, subject to applicable law. |
|
RNOR |
Foreign income is generally outside the Indian tax scope unless specific rules apply, including certain income connected with a business controlled in or profession set up in India. |
|
ROR |
Generally subject to Indian tax on worldwide income, subject to applicable provisions and relief. |
RNOR status is not automatic for every returning NRI. Eligibility depends on the statutory conditions and your residence history.
For example, two professionals returning from the USA in the same year may have different Indian tax outcomes because their previous residence history, days in India and income sources differ.
Foreign income is not automatically tax-free after relocation. Its treatment depends on your Indian residential status, the source and nature of the income, when it is earned or received, and any applicable exceptions.
A returning NRI should review income categories separately rather than treating all US assets and earnings alike.
The distinction between an asset's value and the income generated by that asset is important. Simply holding a US brokerage account or retirement account does not mean its entire balance is automatically taxable as income in India.
Keep records of purchase prices, acquisition dates, distributions, withholding taxes and previous tax filings. These details can help establish the correct tax treatment when you sell assets or receive income after relocating.
 Also Want to Know About DTAA Benefit for NRI Accounts Check Now!
Moving to India does not necessarily end your US tax obligations. The outcome depends on whether you are a US citizen, a green-card holder or another type of US taxpayer.
US citizens generally remain subject to US federal income-tax rules on worldwide income, regardless of where they live. Filing obligations depend on applicable requirements, but relocating to India does not itself end those obligations.
Green-card holders need to examine their US tax residency and immigration status separately. Ending US tax residency can involve specific legal and procedural requirements; simply leaving the country or allowing a green card to expire does not necessarily resolve the tax position.
People who are no longer US tax residents may still have US filing or tax obligations on certain US-source income, including qualifying rental income or investment income.
Depending on your circumstances, you may also need to consider US state tax rules, reporting requirements for foreign financial accounts or assets, and the tax treatment of deferred compensation.
The IRS provides guidance for US citizens and resident aliens living abroad. Review the rules relevant to your specific status rather than assuming that all former US residents have the same obligations.
The India–US income tax treaty and domestic foreign tax credit provisions may provide relief when the same income is taxable in both countries. However, relief is not automatic, and the amount available depends on the applicable rules.
Before claiming Double Taxation relief, establish:
Eligible taxpayers claiming Indian foreign tax credit may need to submit Form 67 in accordance with the applicable rules and deadlines. Keep evidence of foreign income, tax paid and supporting tax returns.
The Indian Income Tax Department's Form 67 guidance explains the purpose of the form and the foreign tax credit process.
For US-side relief, the IRS also provides guidance on foreign tax credits. The official India–US tax treaty documents should be consulted when treaty provisions are relevant.
A foreign tax credit does not necessarily eliminate all tax payable in either country. The calculations and eligibility conditions must be assessed for the particular income and taxpayer.
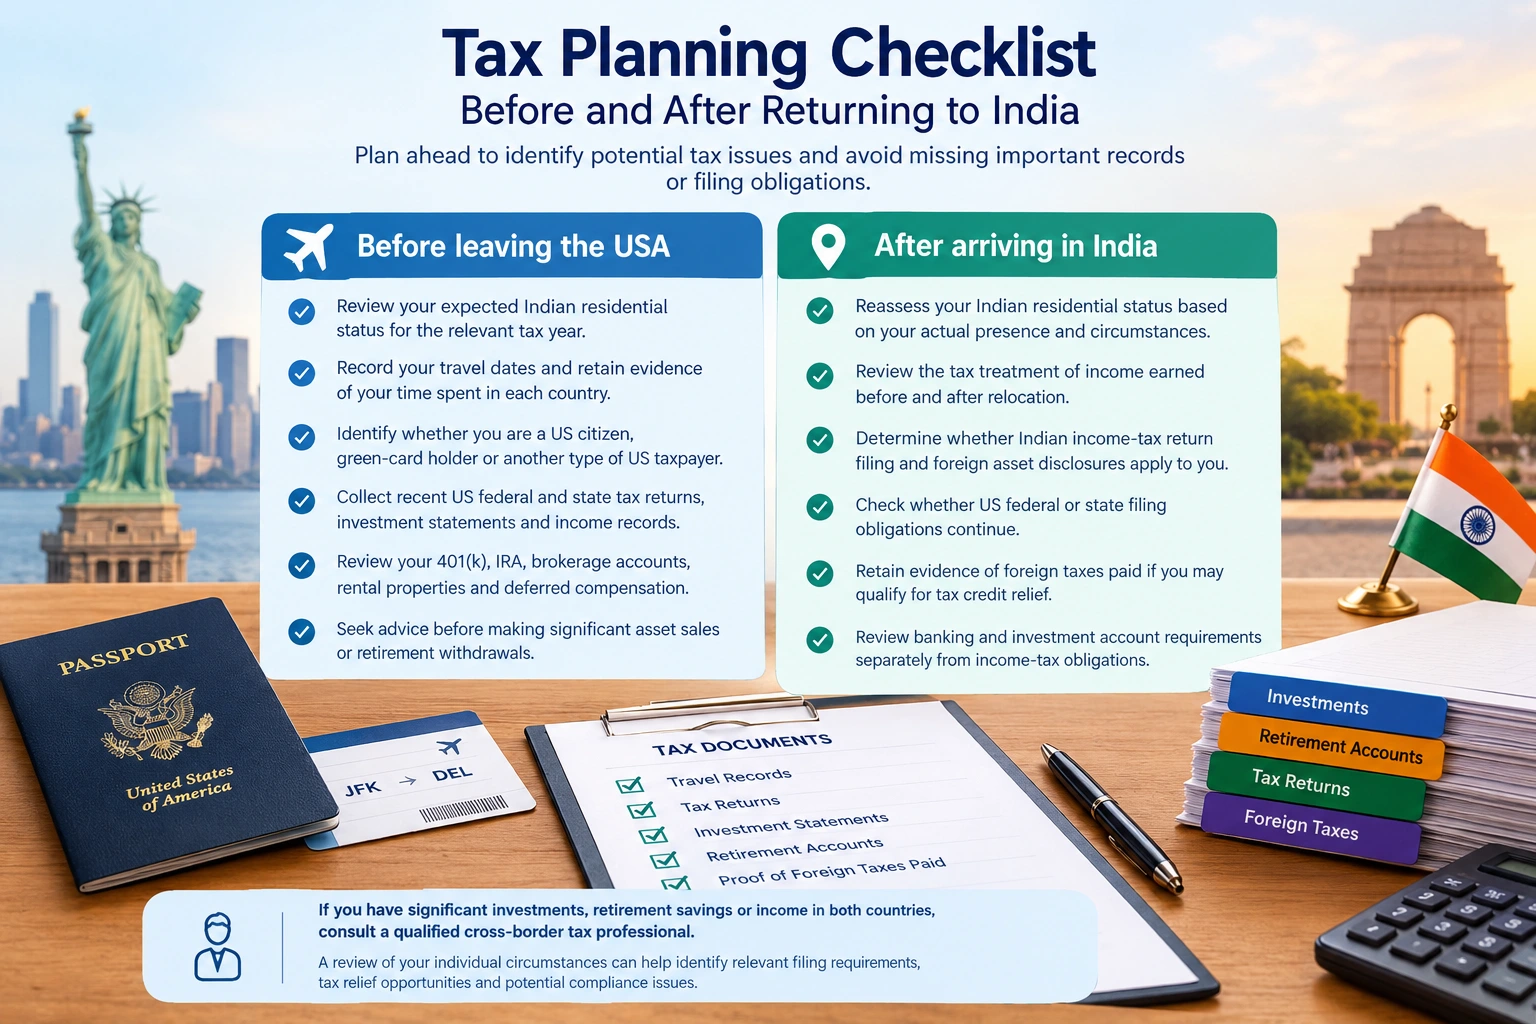
Planning before relocation can help you identify potential tax issues and avoid missing important records or filing obligations.
If you have significant investments, retirement savings or income in both countries, consult a qualified cross-border tax professional. A review of your individual circumstances can help identify relevant filing requirements, tax relief opportunities and potential compliance issues.
Stop worrying about delays. Apply now and get Indian Counsellor Services.
Chat NowFor NRIs returning to India from the USA, the most important tax-planning steps are to determine Indian residential status, understand continuing US tax obligations, review overseas income and assets, and assess eligibility for double-taxation relief. Keep accurate records and verify the rules applicable to the relevant tax year. For complex cross-border situations, seek advice from qualified Indian and US tax professionals before making major financial decisions.
No. RNOR eligibility depends on the applicable statutory conditions and the individual's residence history. Returning to India alone does not establish RNOR status.
Owning a US bank account does not automatically make its full balance taxable as income in India. However, interest earned, applicable reporting requirements and the treatment of the account under your residential status must be reviewed.
Not necessarily. Selling investments can have tax consequences in both countries. Consider the investment, acquisition date, potential gains, tax residency and applicable rules before deciding whether to sell or retain an asset.
When you return to India, you need to convert your NRE account into a residential savings account or an RFC account in a few weeks.
To avoid double taxation in India and the USA, you need a well-planned structure, such as a flow-through or pass-through entity. I this, the profits bypass the corporate taxation and directly foes to the owners.
When you return to India, you need to convert your NRE account into an Indian resident savings account and the funds which is in your NRE account to the resident foreign currency RFC account.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.
When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.