Related Blogs

Returning to India after living and working in the UK can create a number of tax questions: When do you become an Indian tax resident? Can you qualify as RNOR? Will your UK income be taxable in India? What happens to UK pensions, investments and bank accounts?
The answer depends on your Indian residential status, UK tax residence, the timing and source of your income, and the India–UK tax treaty. This guide explains the key tax considerations for an NRI moving back to India and the steps to review before filing your first Indian tax return after the move.
Important: Tax rules can change, and the outcome depends on your individual facts. The information below is general guidance, not personalised tax advice. Verify the applicable rules for the relevant tax year before filing.
Returning to India does not automatically mean that every item of UK income becomes taxable in India from the day you arrive.
The first question is your Indian tax residential status for the relevant tax year. You then need to consider the type and source of each income item, when it arose, your UK tax position and whether the India–UK DTAA affects the result.
For example, imagine an individual leaves the UK in September and moves permanently to India. The person's UK employment income earned before the move, UK bank interest received later, and income from a UK pension are not necessarily treated as one single category. The relevant tax rules can differ for each item.
That is why a returning NRI should avoid using a simple rule such as "I moved to India, so all my UK income is now taxable in India."
For someone returning from the UK, Indian residential status is the starting point for analysing Indian tax liability.
Under the Income Tax Act, 2025, the basic individual residence tests remain unchanged. An individual is generally resident in India if they stay in India for 182 days or more during the relevant tax year, or for 60 days or more during that year and 365 days or more during the preceding four years, subject to the specific statutory exceptions and conditions.
For tax years beginning on or after 1 April 2026, residential status is determined under the Income Tax Act, 2025. The Income Tax Department also confirms that earlier years can remain relevant when applying the continuity-based conditions for determining RNOR status.
Your India arrival date matters because residential status is assessed for each tax year.
India's tax year and the UK's tax year are also different:
As a result, a person who moves from the UK to India during the year may need to analyse the same period under two different tax-year systems.
Keep a record of:
Yes. A returning NRI may qualify as Resident but Not Ordinarily Resident (RNOR) if the applicable statutory conditions are satisfied.
The Income Tax Department's current guidance confirms that continuity-based tests, including the nine-out-of-ten preceding years and 729 days or less during the preceding seven years tests, continue to be relevant for RNOR determination under the new tax-law framework.
RNOR status matters because the Indian tax treatment of foreign income can differ from that applicable to an ordinarily resident taxpayer. However, RNOR is not automatically available to every person returning from the UK. Your residence history and other statutory conditions must be checked for the relevant year.
Moving to India does not automatically terminate your UK tax residence.
HM Revenue & Customs (HMRC) determines UK residence under the Statutory Residence Test (SRT). The test considers factors including the number of days spent in the UK, applicable automatic tests and, where necessary, your connections with the UK. Each UK tax year is considered separately.
The UK tax year runs from 6 April to 5 April of the following year.
If you leave the UK during a tax year, split-year treatment may apply, but it is not simply an automatic consequence of moving abroad.
HMRC has specific split-year cases and conditions. Where the relevant conditions are satisfied, a UK tax year can be divided into a UK part and an overseas part for certain tax purposes.
This distinction can be important when analysing income and gains arising around the date you move to India.
If you leave the UK to live abroad permanently, HMRC says you should tell them. Depending on whether you normally file Self Assessment and your circumstances, you may need to report your departure through your tax return or use form P85.
If you continue to have UK income after moving, such as rental income or pension income, your UK tax obligations may continue even after you become non-UK resident. Your departure therefore should not be treated as the end of all UK tax considerations.
There is no single tax rule for all UK income. The relevant treatment can depend on your Indian residential status, the type of income, when it arose, where it arose and applicable treaty provisions.
|
UK income or asset |
What a returning NRI should review |
|---|---|
|
UK salary |
Identify where and when the employment was performed and when the income arose, particularly around the date of relocation. |
|
UK bank interest |
Consider whether the interest is taxable or reportable in India based on your residential status and the applicable rules. |
|
UK dividends |
Review Indian taxation, UK-source taxation and potential treaty/foreign-tax-credit implications. |
|
UK rental income |
Moving to India does not eliminate UK tax considerations for UK property income. |
|
UK pension/annuity |
The pension type, residence status and treaty provisions can affect the tax treatment. |
|
UK investments |
Interest, dividends and gains should be analysed separately rather than treating the investment account as one item. |
|
Capital gains |
Consider both Indian and UK residence rules and the nature and location of the underlying asset. |
The important distinction is between owning an asset and receiving income or gains from that asset. A UK bank account containing money accumulated while you were living in the UK is not the same tax question as interest subsequently earned on that account.
The same principle applies to investments: the existence of a UK investment account does not, by itself, answer whether a particular dividend, interest payment or capital gain is taxable in India.
Returning to India does not necessarily mean that you must immediately close every UK financial account.
However, once you become subject to Indian reporting requirements, you should review your foreign bank accounts, securities, investments and foreign-source income carefully.
The correct reporting treatment depends on your residential status and the relevant Indian tax-return requirements. Do not assume that an account is irrelevant simply because the money was accumulated while you were living in the UK.
A useful approach is to prepare a foreign-asset and income record containing:
The Indian tax return and applicable schedules should then be completed based on your status and circumstances for that tax year. Because reporting rules can change, check the current Income Tax Department instructions for the relevant ITR form and tax year before filing.
The India–UK Double Taxation Convention (DTAA) is important when the same income may potentially be taxed in both countries.
However, the DTAA should not be understood as a blanket exemption from tax in either country. Different treaty provisions apply to different categories of income.
For example, the India–UK convention contains provisions dealing with interest, dividends, employment income, pensions and other categories of income, along with provisions intended to provide relief from double taxation.
The practical question is therefore not simply:
"I already paid UK tax, so do I owe nothing in India?"
Instead, the analysis should consider:
For a return involving significant UK investments, pensions, property or capital gains, professional review can be worthwhile because treaty treatment can become fact-specific.
Your first Indian tax return after returning from the UK deserves particular attention.
Before filing, establish:
Do not select an ITR form simply because you previously filed a particular form as an NRI. Your residential status and income profile may have changed.
Foreign-income and foreign-asset reporting also should not be treated as interchangeable concepts. The applicable ITR schedules depend on the taxpayer's circumstances and the tax year, so the current Income Tax Department instructions should be checked before filing.
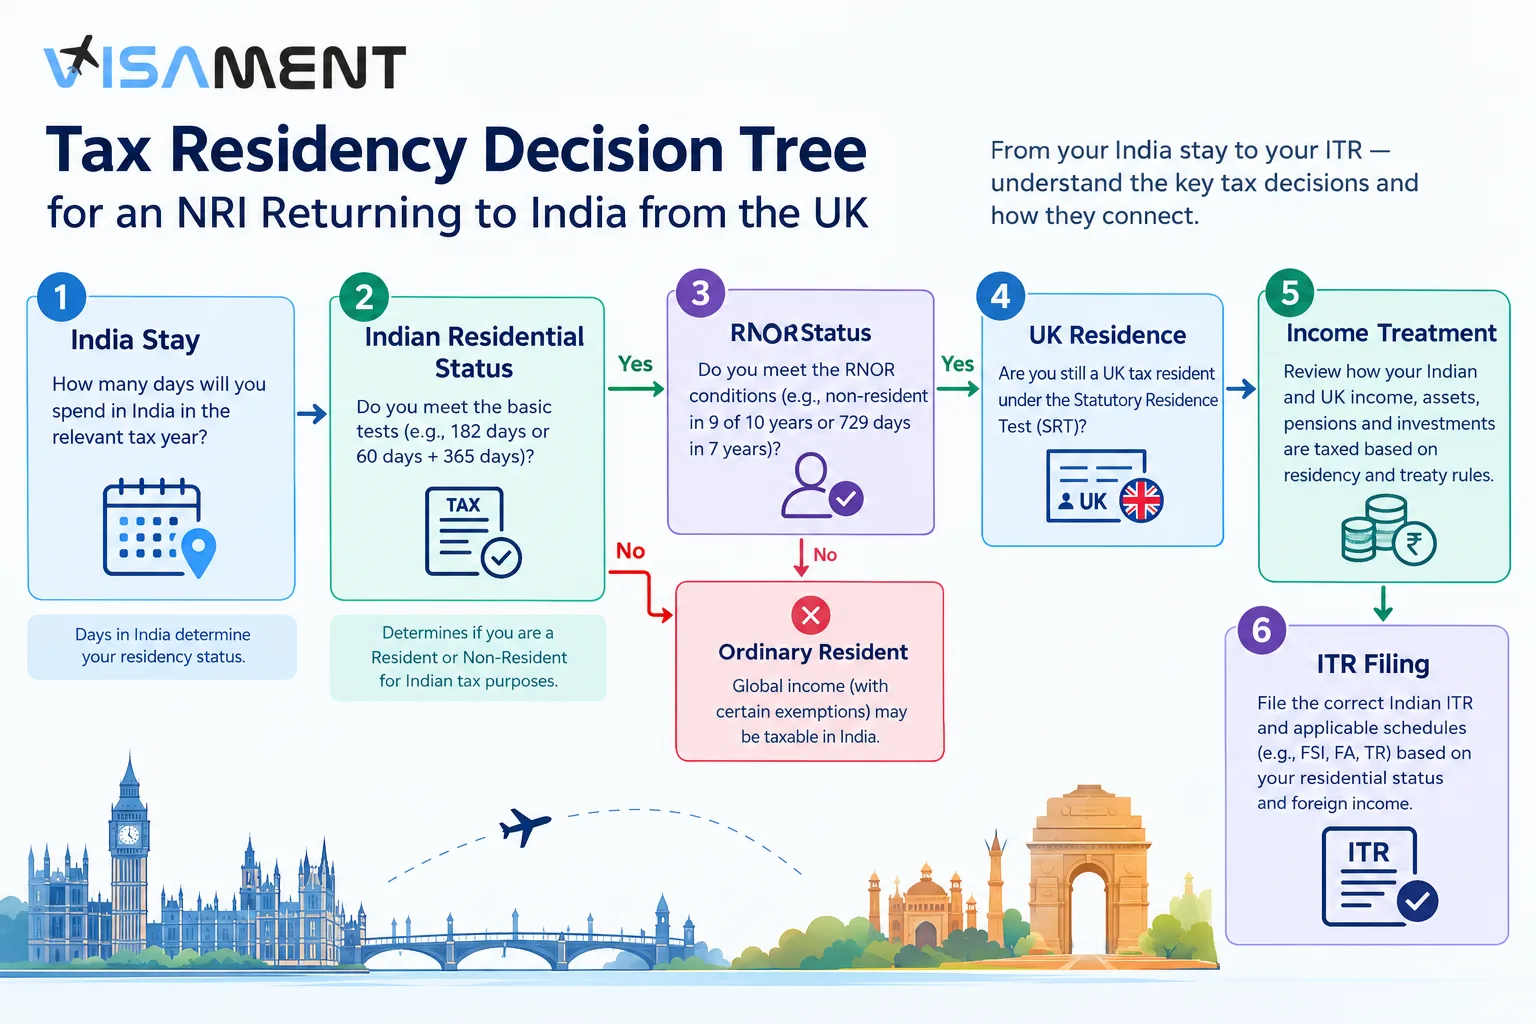
Indian residential status is determined under statutory tests. Your physical relocation date is important, but it is not the only factor.
Salary, bank interest, dividends, rental income, pensions and capital gains can be subject to different rules.
HMRC's SRT applies independently, and split-year treatment has specific conditions.
The Indian tax year runs from 1 April to 31 March, while the UK tax year runs from 6 April to 5 April. This can make the year of relocation particularly important.
A tax treaty does not automatically make income tax-free. Its provisions must be applied to the particular income and residence circumstances.
Owning a UK account or investment and receiving income from that account or investment are separate questions. Reporting obligations also depend on the taxpayer's status and applicable ITR requirements.
Stop worrying about delays. Apply now and get Indian Counsellor Services.
Chat NowFor an NRI returning to India from the UK, the most important tax step is to determine the correct residential status for the relevant Indian tax year. From there, review RNOR eligibility, your UK residence position, income earned around the relocation date, UK pensions and investments, foreign assets, and the potential application of the India–UK DTAA.
The safest approach is to treat the move as a cross-border tax transition rather than simply a change of address. Keep your UK and Indian dates, income and tax records organised, verify the current rules before filing, and seek professional advice where pensions, investments, property or significant foreign income make the situation more complex.
After your return to India from the UK, you will become a resident if you stay for more than 182 days in a financial year. You may also be eligible for RNOR status for up to 3 years, which provides many tax benefits.
At the RNOR rate, most applicants are exempt from tax in India on overseas income, including UK earnings. Your global income is also taxed only once when you become an ordinary resident.
The DTAA agreement between India and the UK helps avoid double taxation and allows you to claim taxes paid in the UK and use those credits to offset your Indian tax liability on the same income.
After you return to India and your residential status changes to resident, you need to convert your NRE/NRO bank accounts into resident savings accounts. However, you can continue to use your FCNR accounts until maturity.
You can update your PAN card and Aadhar card through the official government website, through offline or online methods, by filing a form and providing all the details.
Yes, you need to file your tax returns in both India and the UK each year, and need to report all your foreign assets in the Indian ITR.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.
When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.