Related Blogs

Selling an asset for more than its relevant cost can create a capital gain, and that gain may be taxable in India. However, the tax is not simply calculated on the total amount you receive from a sale. The applicable treatment can depend on the type of asset, how long you held it, the date of transfer, allowable costs, exemptions and the tax rules applicable for the relevant assessment year.
This guide explains how capital gains tax works in India, how gains are broadly calculated, how short-term and long-term gains differ, what current tax rates apply in relevant cases, and what taxpayers—including NRIs—should consider before filing their income tax return.
Capital gain tax is the tax applicable to taxable profits or gains arising from the transfer of a capital asset. The Income Tax Department states that profit or gain arising from the transfer of a capital asset during the year is generally charged under the head "Capital Gains."
A capital asset can include many forms of property and investments, subject to exclusions and specific provisions under the Income Tax Act. Common examples include:
The important point is that selling an asset for ₹20 lakh does not mean ₹20 lakh is automatically taxable as capital gain. The calculation generally considers the relevant sale consideration and allowable costs or adjustments prescribed for that asset and transaction.
For example, if an asset is sold for ₹20 lakh and its relevant cost is ₹14 lakh, the starting point for the gain may be ₹6 lakh before considering applicable expenses, adjustments, exemptions or other statutory provisions.
The basic concept can be represented as:
Capital Gain = Relevant Sale Consideration − Allowable Costs and Adjustments
Depending on the asset and applicable rules, the calculation may involve:
The exact formula is not identical for every asset. For example, taxation of listed securities, property, mutual funds and other investments can involve different provisions.
Suppose an investor purchases an asset for ₹10 lakh and later sells it for ₹15 lakh. If ₹50,000 of the selling-related expense is allowable under the applicable rules, the initial calculation could be:
₹15,00,000 − ₹50,000 − ₹10,00,000 = ₹4,50,000
The ₹4.5 lakh figure is an illustrative capital gain before considering any asset-specific adjustments, exemptions, losses or applicable tax rules.
Therefore, taxpayers should not calculate their final tax liability merely by subtracting the purchase price from the selling price.
One of the most important steps in calculating capital gains is determining whether the asset is short-term or long-term.
The classification generally depends on the period for which the asset was held, but there is no single holding-period rule for every type of capital asset. The applicable threshold can vary according to the asset category and the law governing the transaction.
For example, the Income Tax Department's current ITR-2 guidance describes a general 24-month rule for certain capital assets, while specified securities and certain other assets can have different holding-period rules.
|
Factor |
Short-Term Capital Gain |
Long-Term Capital Gain |
|---|---|---|
|
Basic classification |
Depends on the applicable holding-period rule |
Depends on the applicable holding-period rule |
|
Holding period |
Asset-specific |
Asset-specific |
|
Tax rate |
Depends on the applicable provision |
Depends on the applicable provision |
|
Calculation |
Depends on asset and transaction |
Depends on asset and transaction |
|
Exemptions/reliefs |
May differ by asset |
May differ by asset |
The acquisition date and transfer date can therefore be important when determining the applicable tax treatment.
There is no single capital-gains tax rate in India for all assets. The applicable rate depends on factors such as the type of asset, whether the gain is short-term or long-term, the relevant section of the Income Tax Act, the taxpayer's status and the date of transfer.
For AY 2026–27, current Income Tax Department materials contain capital-gain categories including 20% short-term capital gains and 12.5% long-term capital gains in relevant cases. They also identify other capital-gain categories that can be taxed at different rates.
This distinction is important because stating that "capital gains are taxed at 12.5%" or "capital gains are taxed at 20%" without specifying the applicable category can be misleading.
For example, current ITR documentation separately identifies long-term gains taxable at 12.5%, short-term gains taxable at 20%, short-term gains taxable at 30%, and gains taxable at applicable rates.
Taxpayers should therefore verify the rate applicable to their specific asset and transaction for the relevant assessment year rather than relying on a general percentage found online.
Capital gains can arise from the transfer of various assets. Common examples include:
The asset category matters because holding-period rules, tax rates, exemptions and calculation methods can differ.
For detailed property taxation, share taxation or mutual-fund taxation, taxpayers should use the relevant asset-specific guidance rather than applying the general rules in this article.
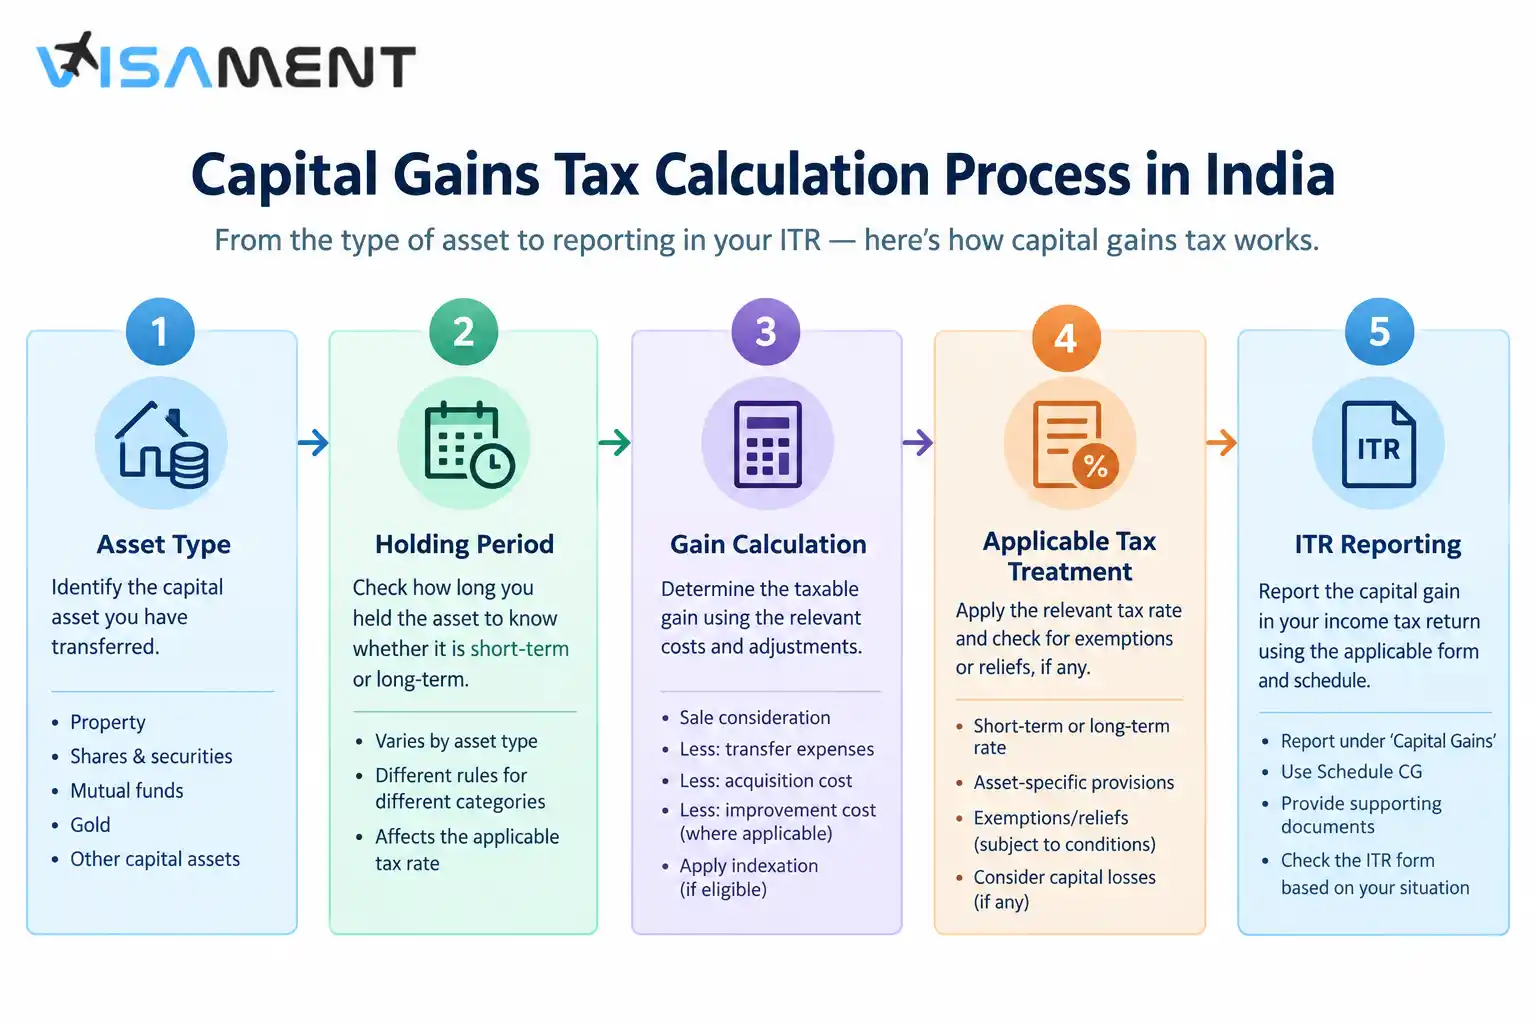
Certain capital gains may qualify for exemptions or other tax relief when the statutory conditions are satisfied. The availability of relief depends on factors such as the asset sold, the nature of the transaction and how the proceeds are used.
For example, the Income Tax Act contains specific provisions relating to exemptions involving certain types of capital assets and reinvestment. These provisions have detailed eligibility conditions and should not be treated as a general deduction available against every capital gain.
It is also important to distinguish between reducing a taxable gain under an applicable exemption provision and simply reducing tax through ordinary deductions. Capital-gains taxation has its own rules, and the relevant section should be checked before claiming an exemption.
A capital loss occurs when the relevant tax computation produces a loss rather than a gain. Subject to the applicable rules, capital losses can potentially be set off against eligible capital gains and may also be carried forward in certain circumstances.
The treatment is not unlimited. The type of loss, the type of gain against which it is being adjusted and whether the applicable return and filing conditions are satisfied can matter.
When filing an ITR, taxpayers should retain the documents supporting both gains and losses. The Income Tax Department's current ITR-2 guidance specifically notes that taxpayers with capital-gain transactions may need transaction statements and documents supporting losses.
Capital gains are reported under the Capital Gains head of income in the applicable income tax return.
The appropriate ITR depends on the taxpayer's circumstances. For example, the Income Tax Department states that ITR-2 can be used by eligible individuals and HUFs having income under the head "Capital Gains," whether short-term or long-term, when they do not have income chargeable under "Profits and Gains of Business or Profession."
The ITR contains Schedule CG for reporting capital-gains income, with different categories for different types of gains. Current AY 2026–27 materials also reflect changes in capital-gains reporting compared with earlier years.
Before filing, taxpayers should reconcile their calculations with relevant records such as:
The Income Tax Department specifically recommends having capital-gain transaction summaries for shares or securities when computing capital gains for ITR purposes.
NRIs can also have Indian capital-gains tax obligations when they transfer assets or investments that are subject to Indian taxation.
The applicable treatment can depend on:
NRI tax implications on capital gains can be more complex than simply applying the general resident taxpayer rules. Current ITR documentation contains specific provisions for non-residents, including different capital-gain categories and DTAA-related reporting.
For example, current rules distinguish certain long-term gains involving immovable property and non-resident taxpayers, while indexation treatment can also differ. The current AY 2026–27 ITR validation rules specifically contain non-resident provisions concerning indexation and capital gains on land or buildings.
NRIs with substantial or complex transactions should therefore verify the applicable Indian tax provisions and treaty position before filing.
Consider a hypothetical investor who buys an asset for ₹12 lakh and later sells it for ₹18 lakh.
If ₹40,000 of the transaction expenses are allowable under the relevant tax rules, the initial gain calculation would be:
Sale consideration: ₹18,00,000
Less: allowable transfer expense: ₹40,000
Less: acquisition cost: ₹12,00,000
Illustrative gain:₹5,60,000
This ₹5.6 lakh figure is only an example of the calculation concept. The final taxable gain and tax payable could differ depending on the asset, holding period, applicable tax rate, exemptions, losses and other provisions.
For that reason, a capital-gains calculation should always begin by identifying what was sold, when it was acquired, when it was transferred and which tax provision applies.
Before calculating a capital gain, gather:
If the transaction involves property, substantial investments, inherited assets, multiple jurisdictions or complicated NRI tax considerations, professional review can help identify provisions that a basic calculation may miss.
Stop worrying about delays. Apply now and get Indian Counsellor Services.
Chat NowCapital gain tax in India is not determined by a single formula or tax rate for every transaction. The correct calculation depends on the asset, acquisition and transfer dates, relevant costs, holding-period classification, applicable tax provision, exemptions and the taxpayer's circumstances.
The safest approach is to identify the specific asset and applicable rules first, calculate the taxable gain using the relevant provisions, and then report it correctly in the applicable ITR. Because capital-gains rules can change, always verify current rates and filing requirements with the latest Income Tax Department guidance before submitting a return.
No. Different assets can have different holding-period rules, tax rates, exemptions and calculation requirements.
The distinction generally depends on how long the capital asset was held, but the applicable holding-period threshold varies according to the asset and relevant tax provisions.
An NRI may have Indian capital-gains tax obligations depending on the asset, transaction, residency status and applicable Indian tax and treaty provisions.
Capital losses may be eligible for set-off or carry-forward subject to the specific rules governing the type of loss, the gain and the applicable filing conditions.
Vipul Jain is the Co-Founder of Visament, a trusted platform dedicated to simplifying Indian immigration, consular, and NRI services for applicants across the globe. With extensive expertise in OCI cards, Indian passport services, visa assistance, apostille and document legalization,... See Full Bio
Talk to our documentation experts for free guidance on your application.
When you visit a website, it may store data about you using cookies and similar technologies. Cookies can be important for the basic operations of the website and for other purposes. You get the option of deactivating certain types of cookies, even so, doing that may affect your experience on the website.
It is required to permit the basic functionality of the website. You may not disable necessary cookies.
Used to provide advertising that matches you and your interests. May also be used to restrict the number of times you see an advertisement and estimate the effectiveness of an advertising campaign. The advertising networks place them after obtaining the operator's permission.
Permits the website to recognize the choices you make (like your username, language, or the region you are in). Also provides more personalized and enhanced features.
Aid the website operator to determine how the website performs, how visitors interact with the site, and whether there are any technical issues.